2020 Financial Calendar
2020 Financial Calendar
Financial Calendar for 2020 – All the dates you need to know to maximize your benefits!
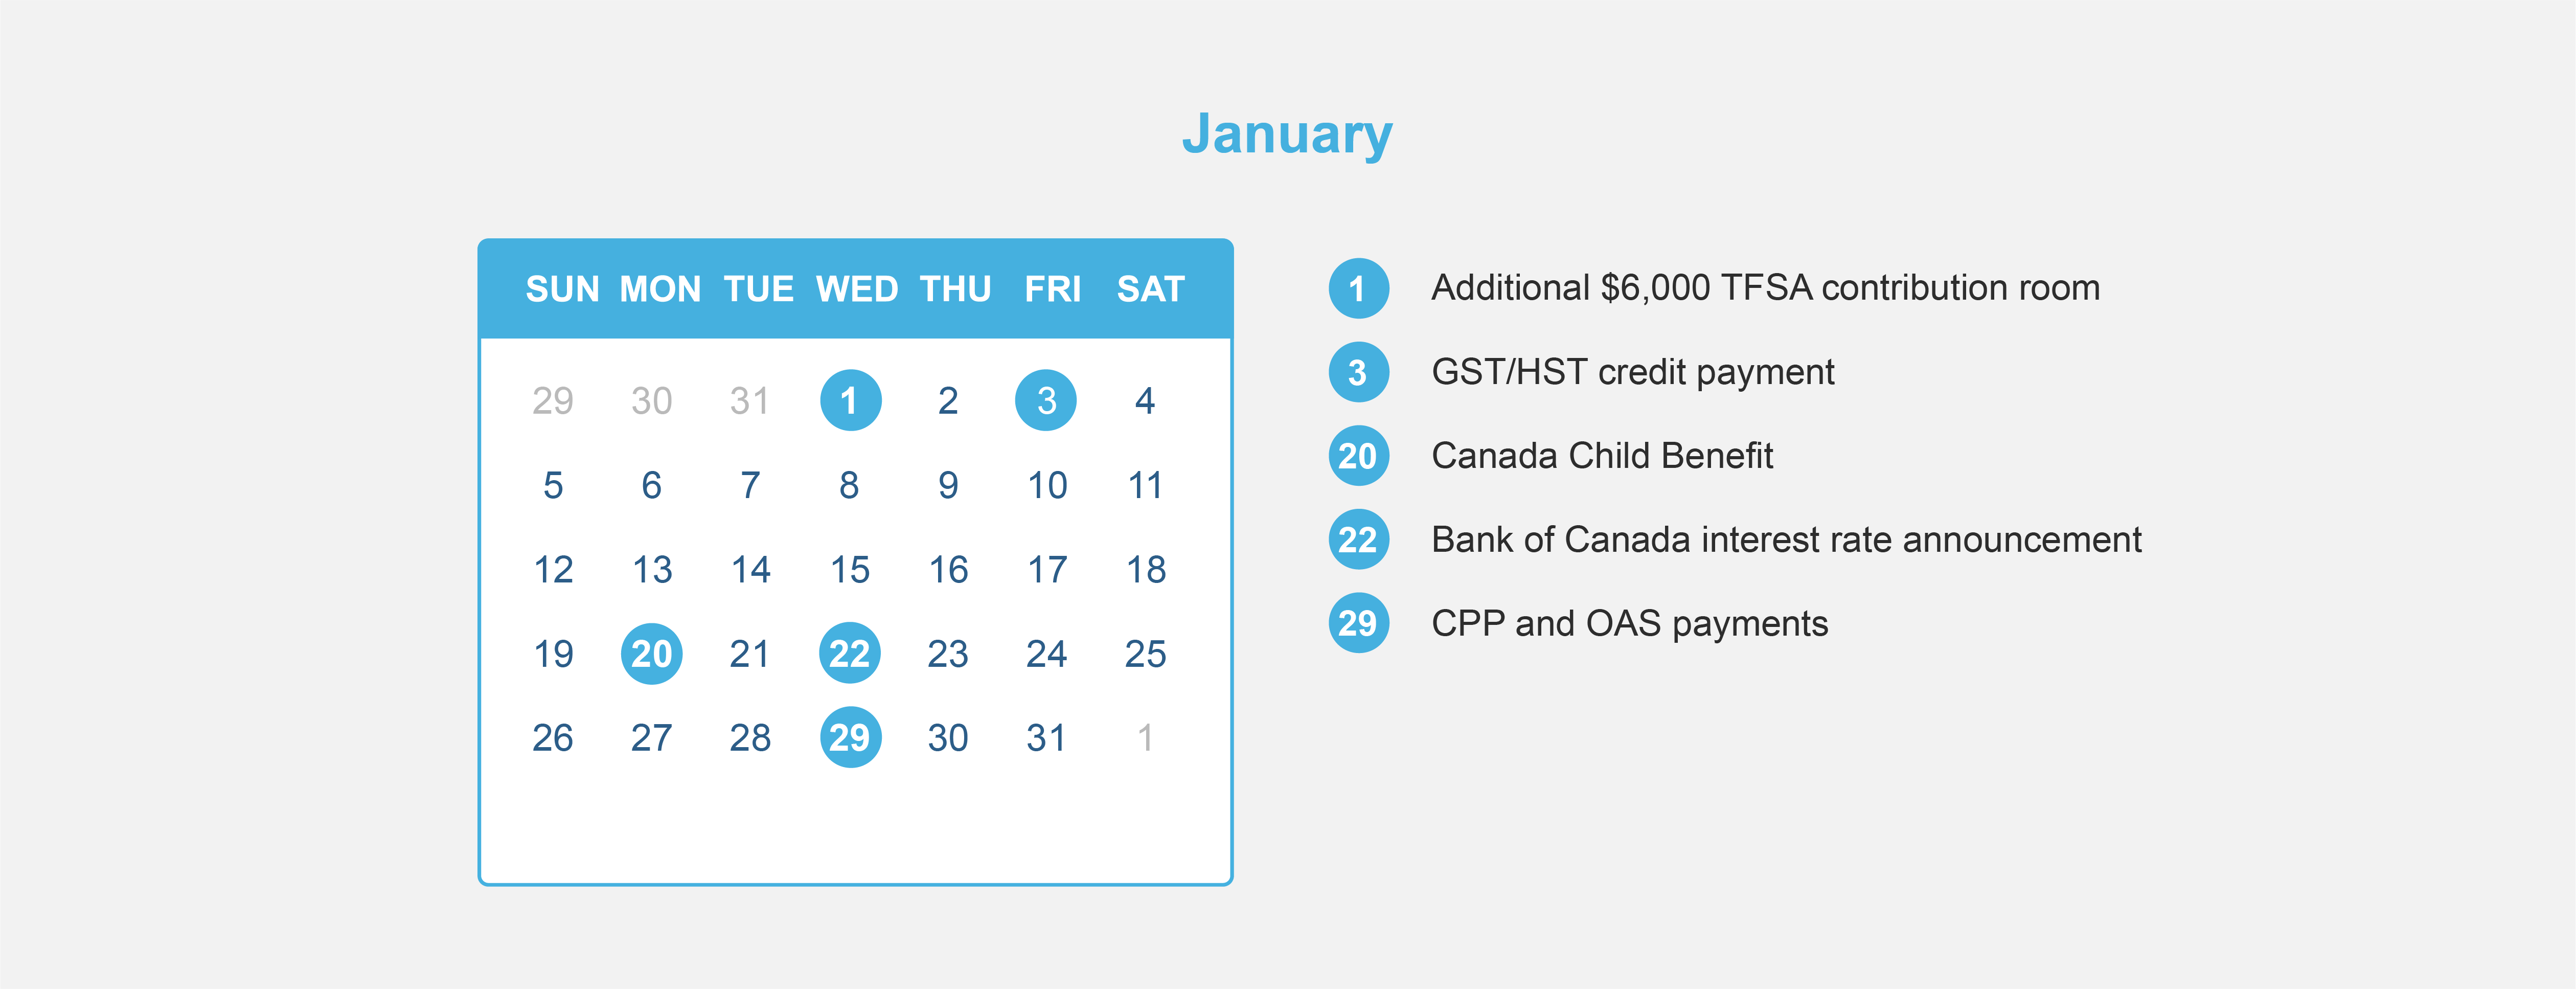
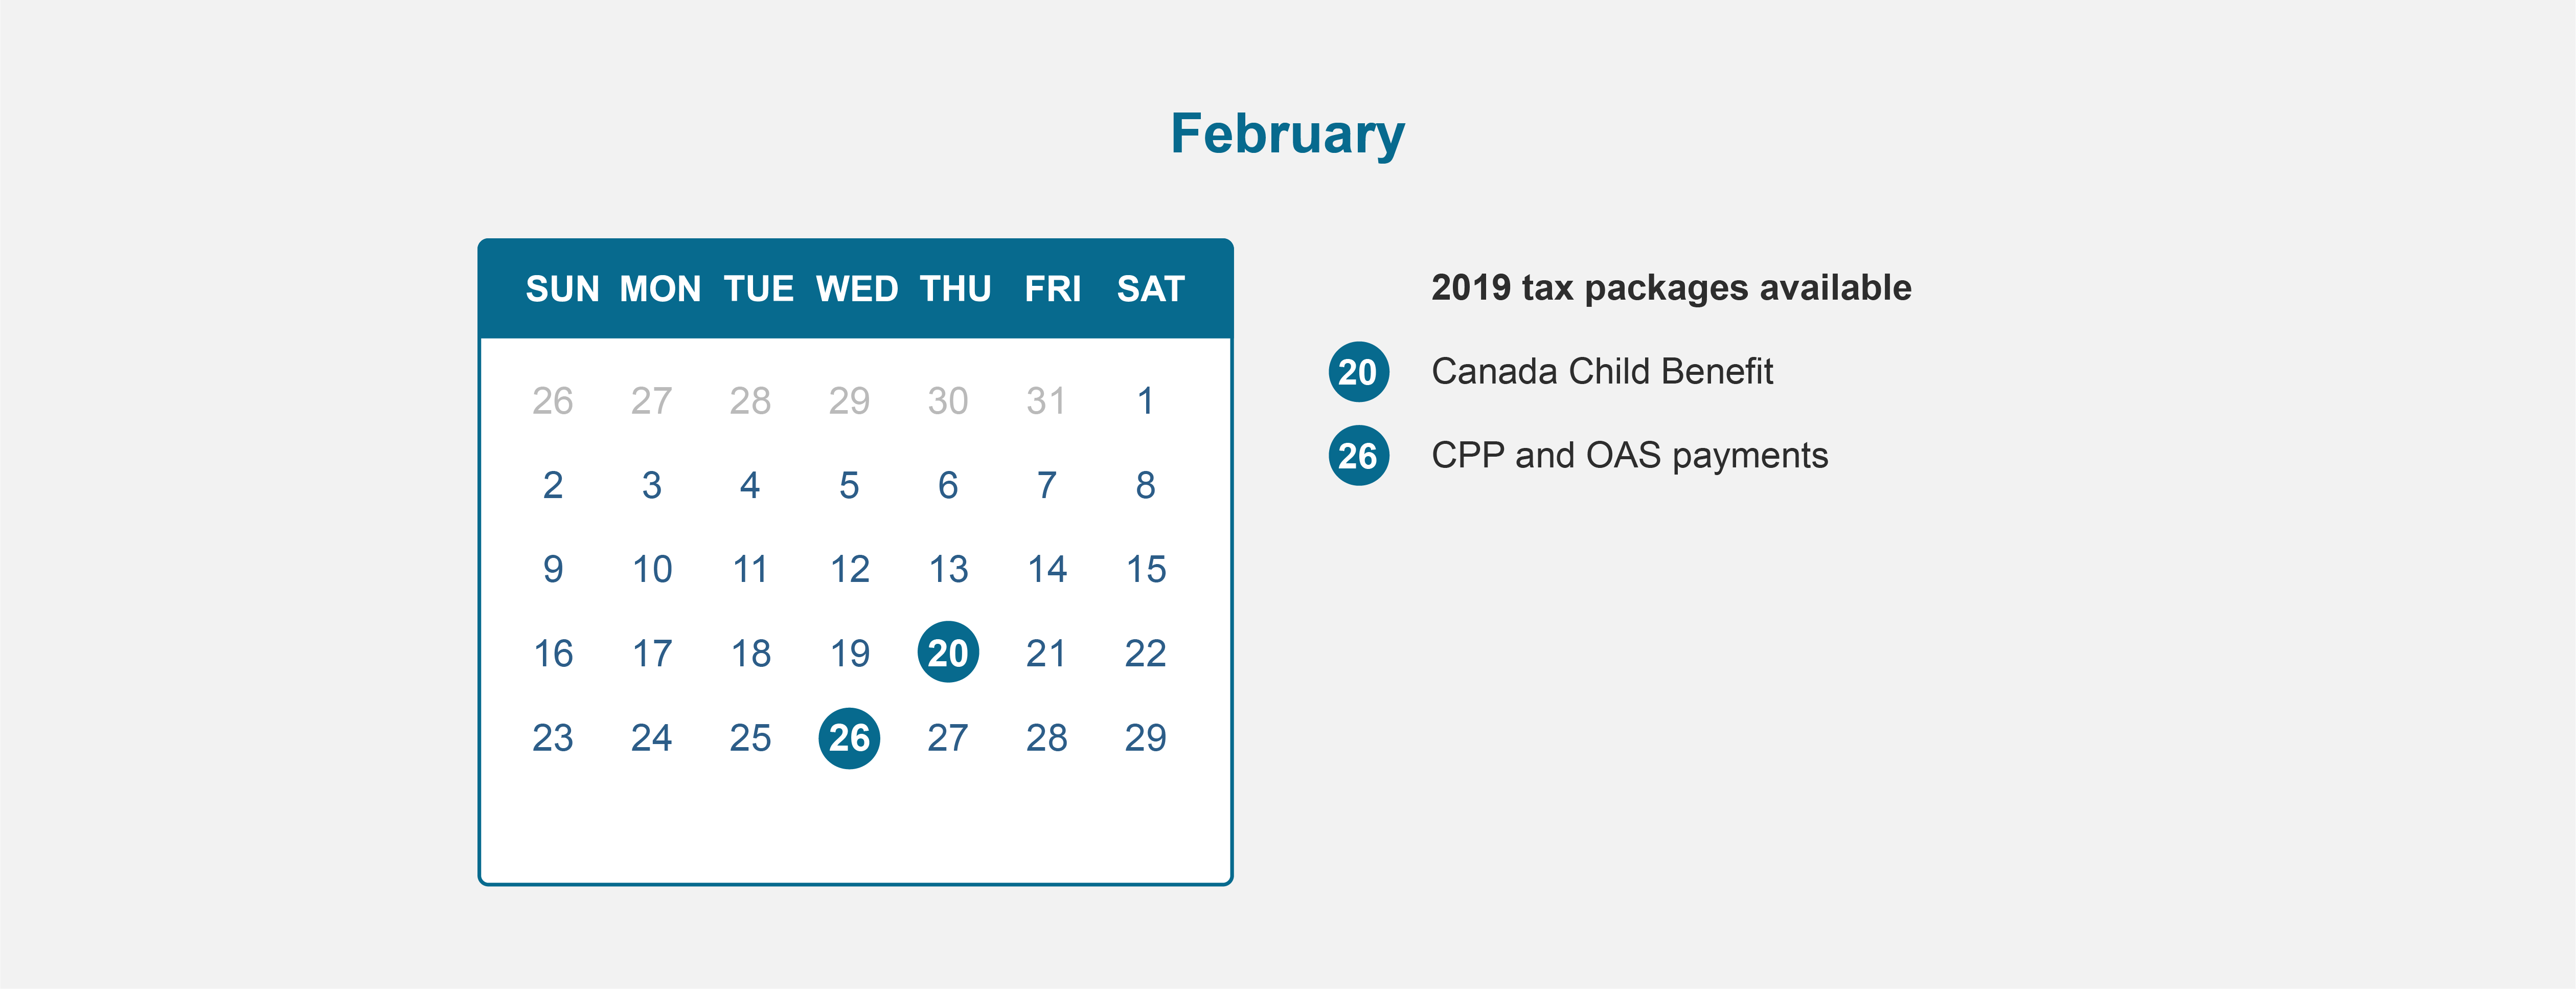
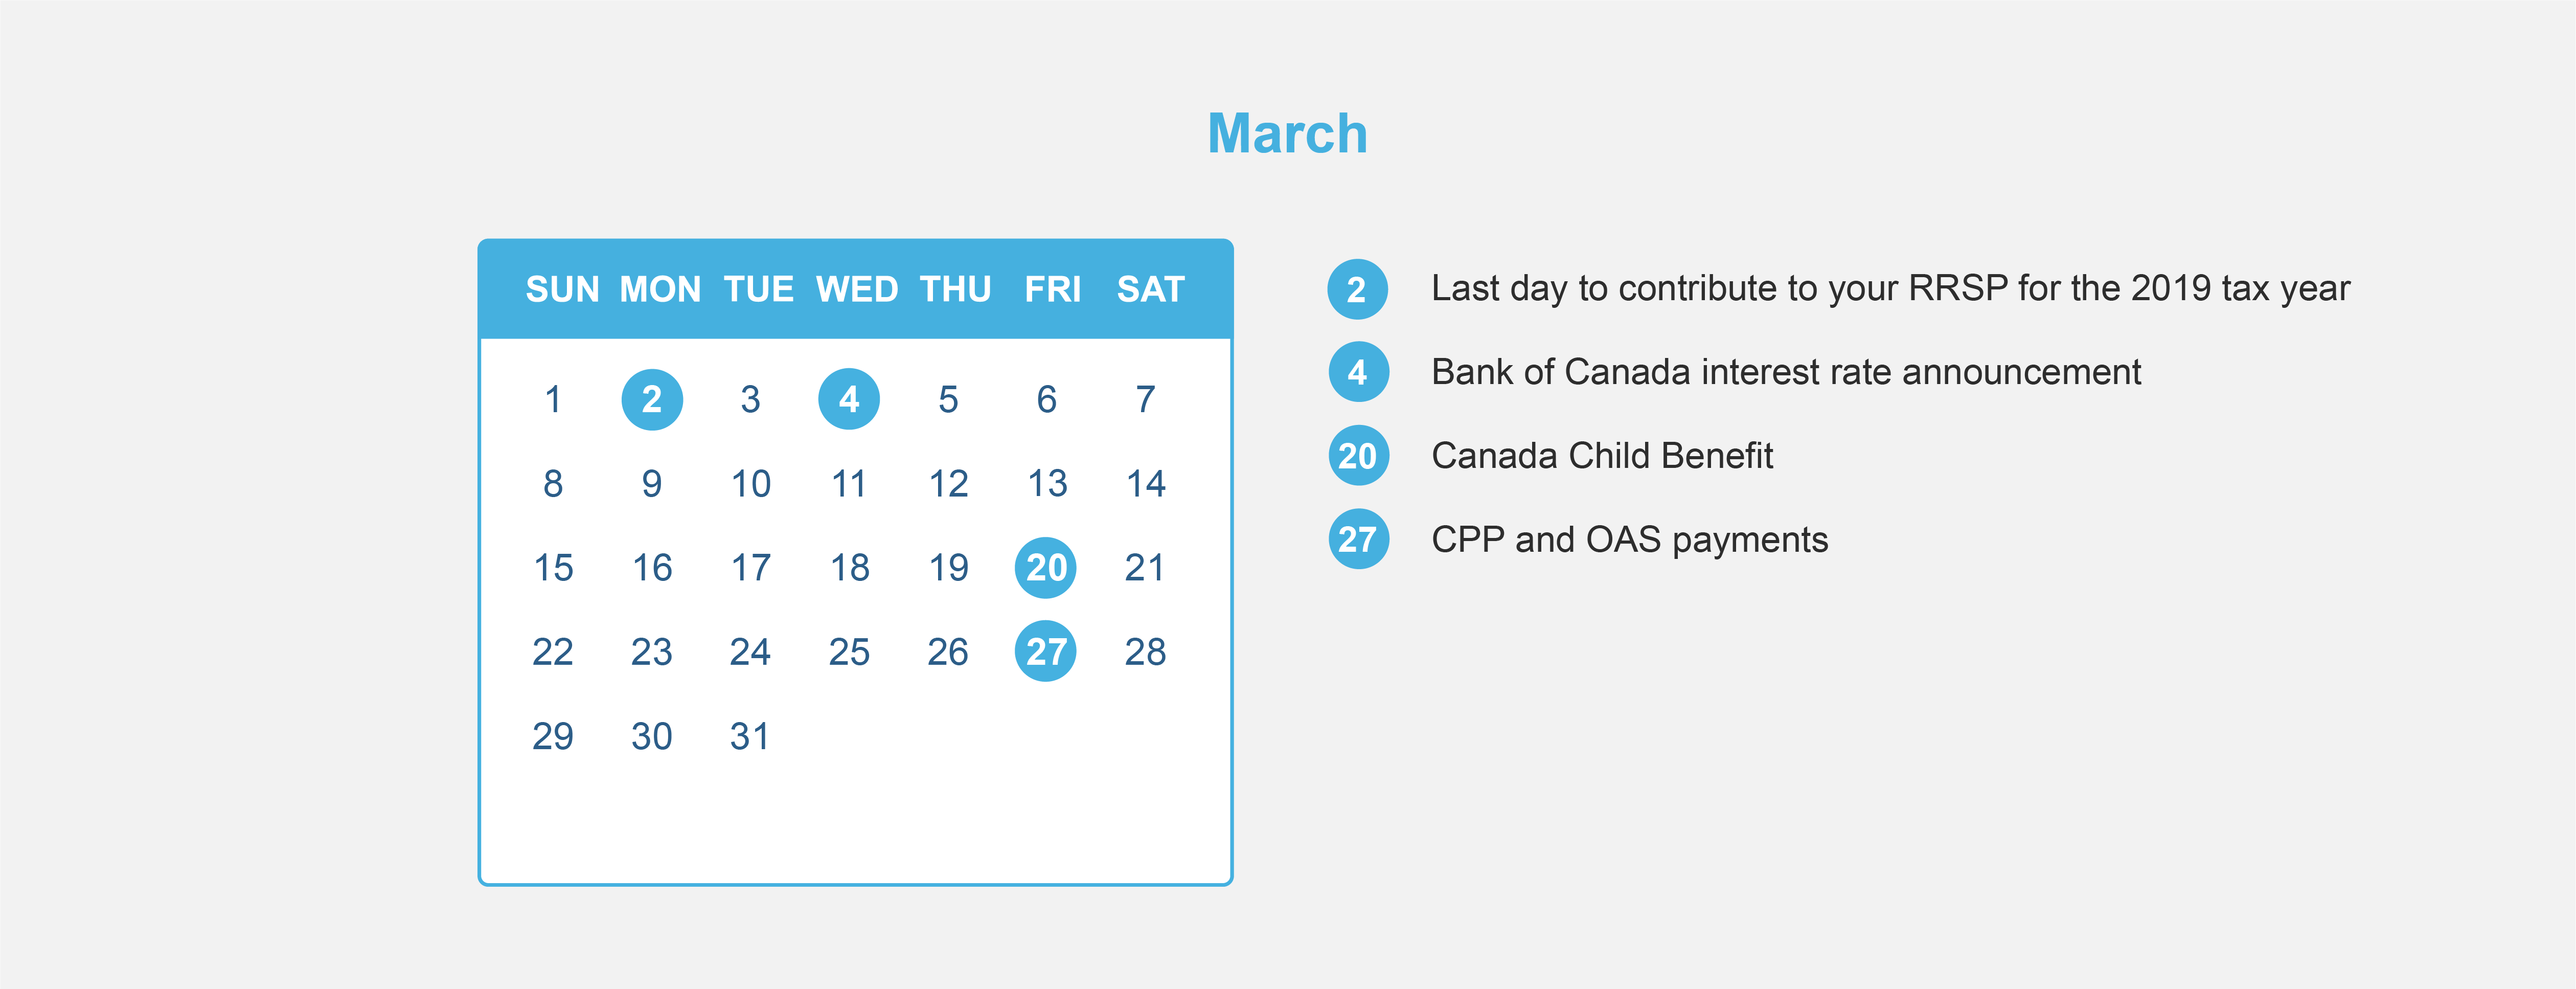
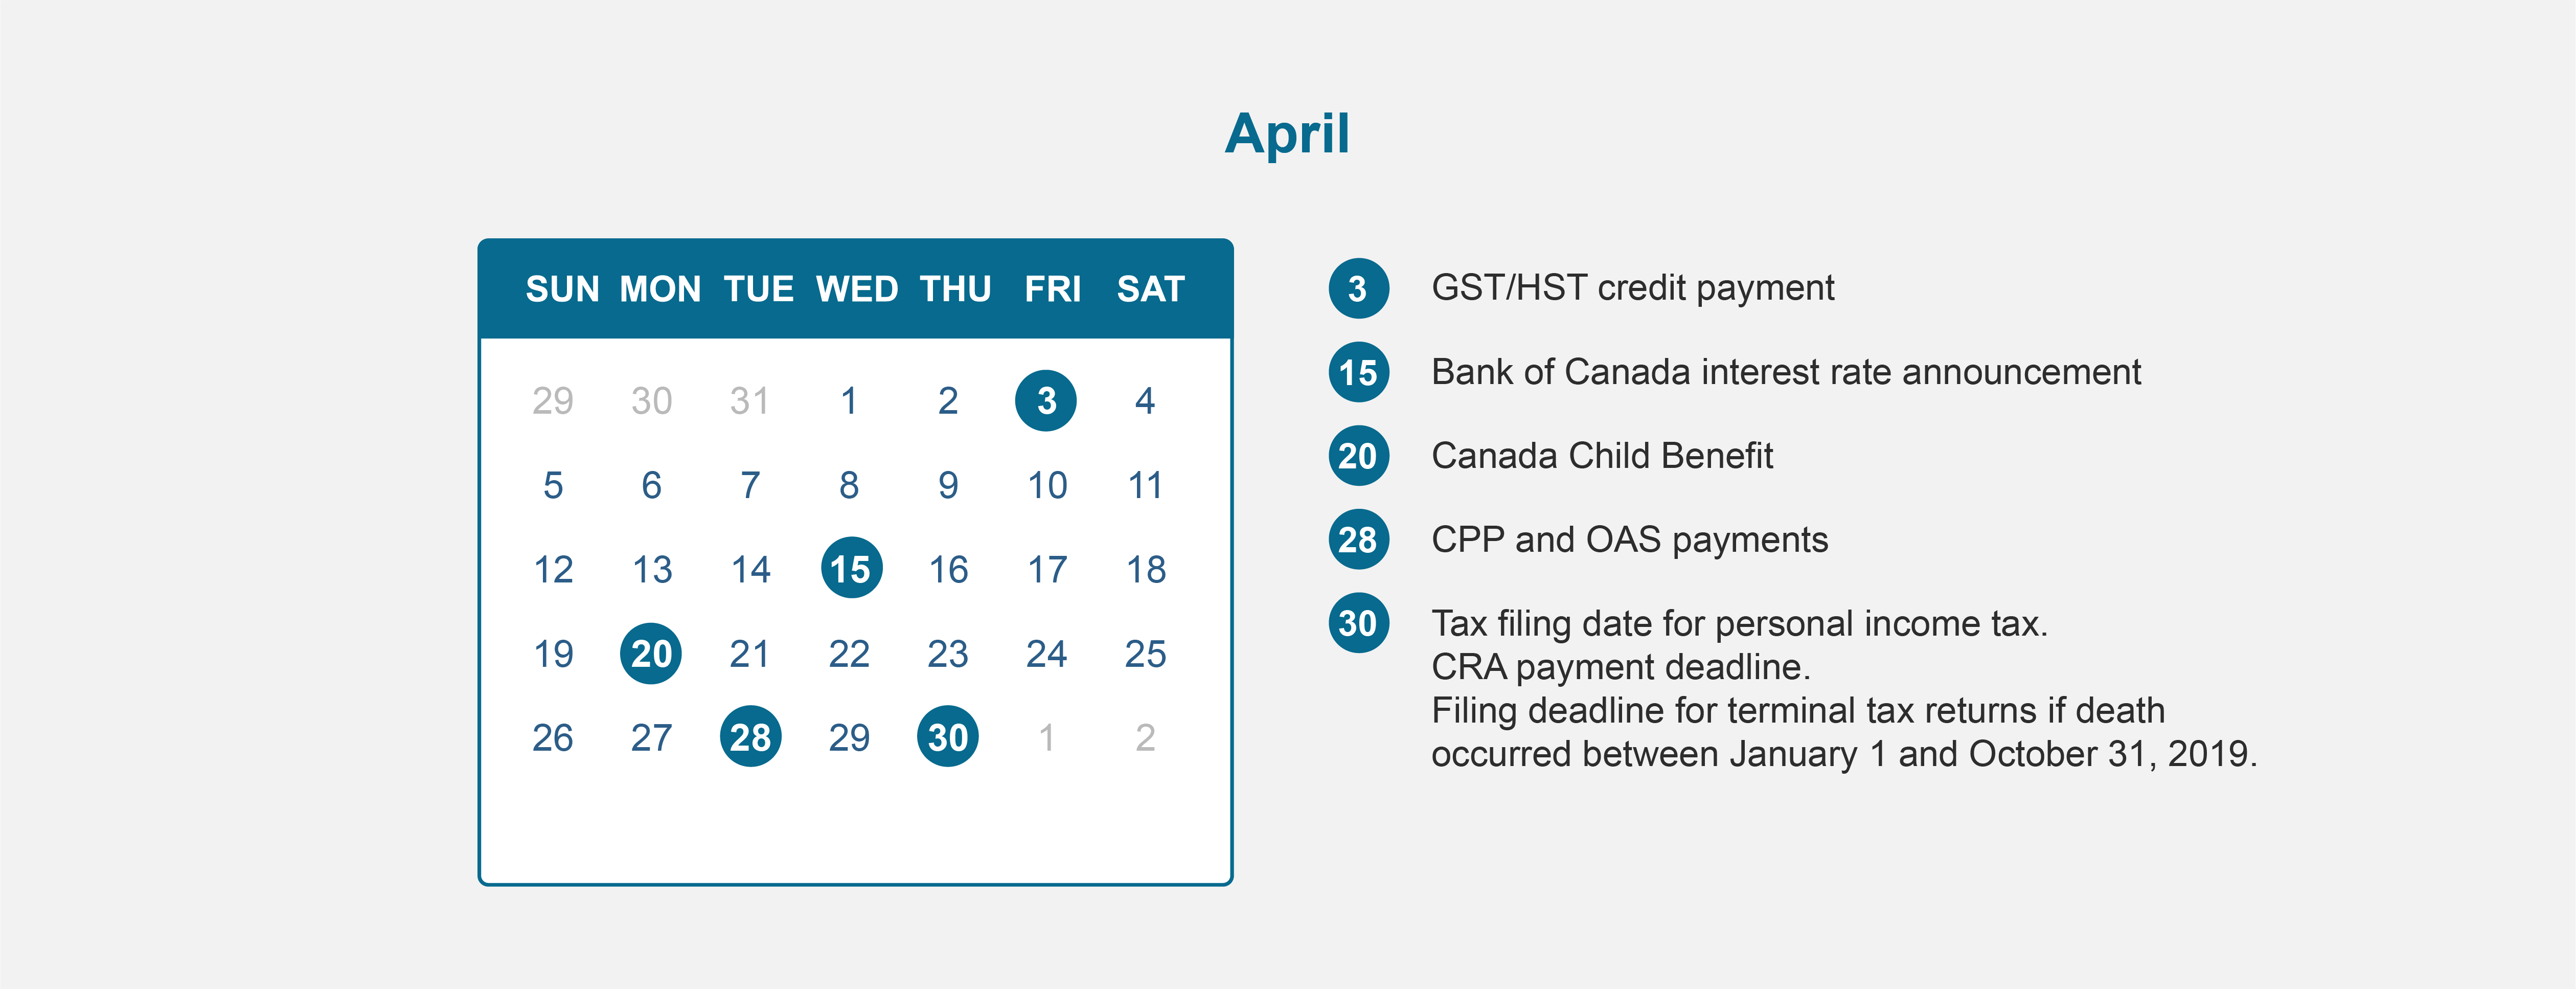
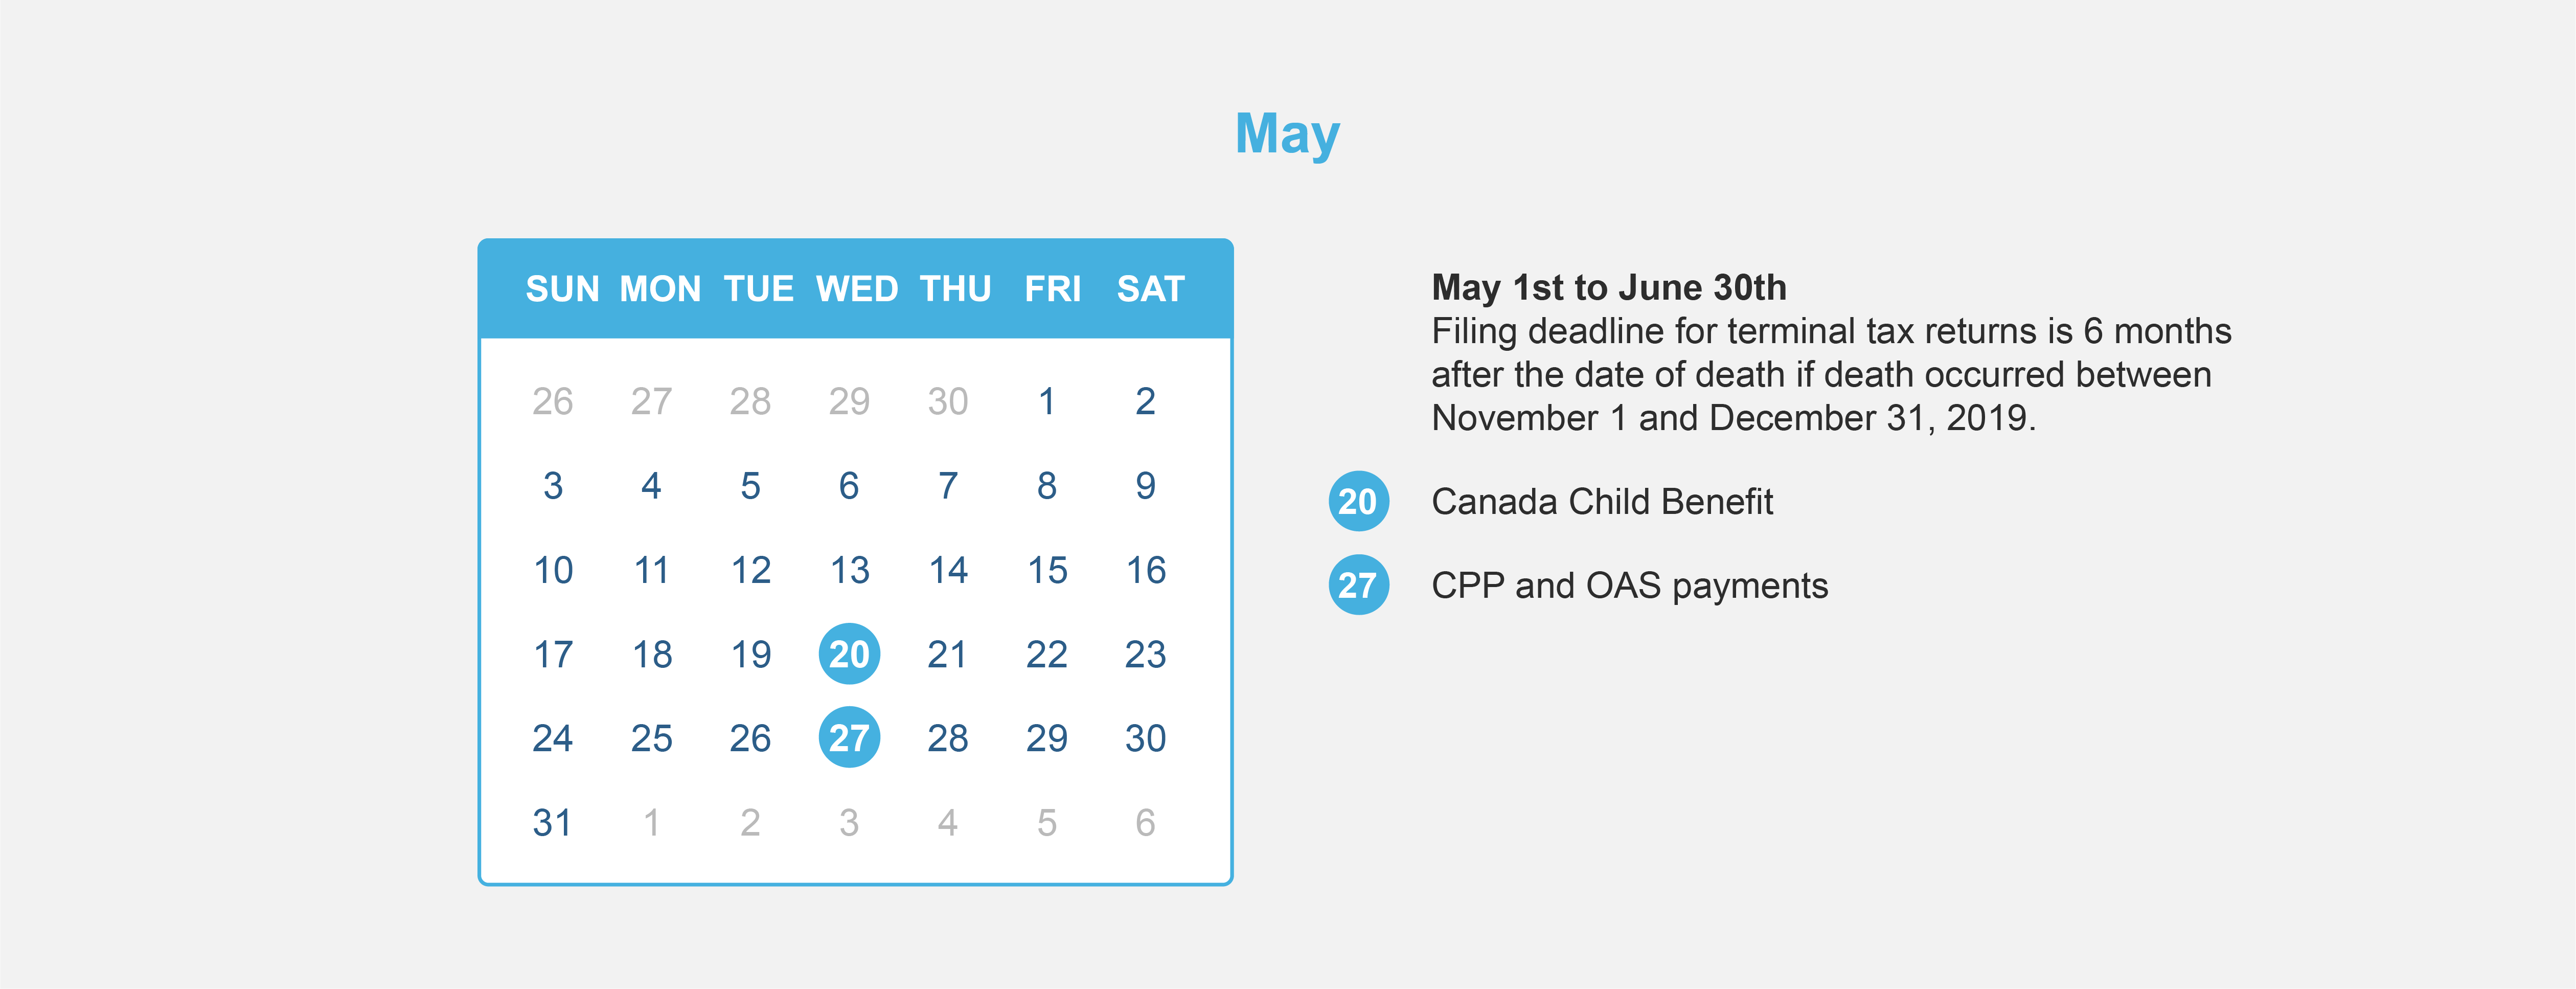

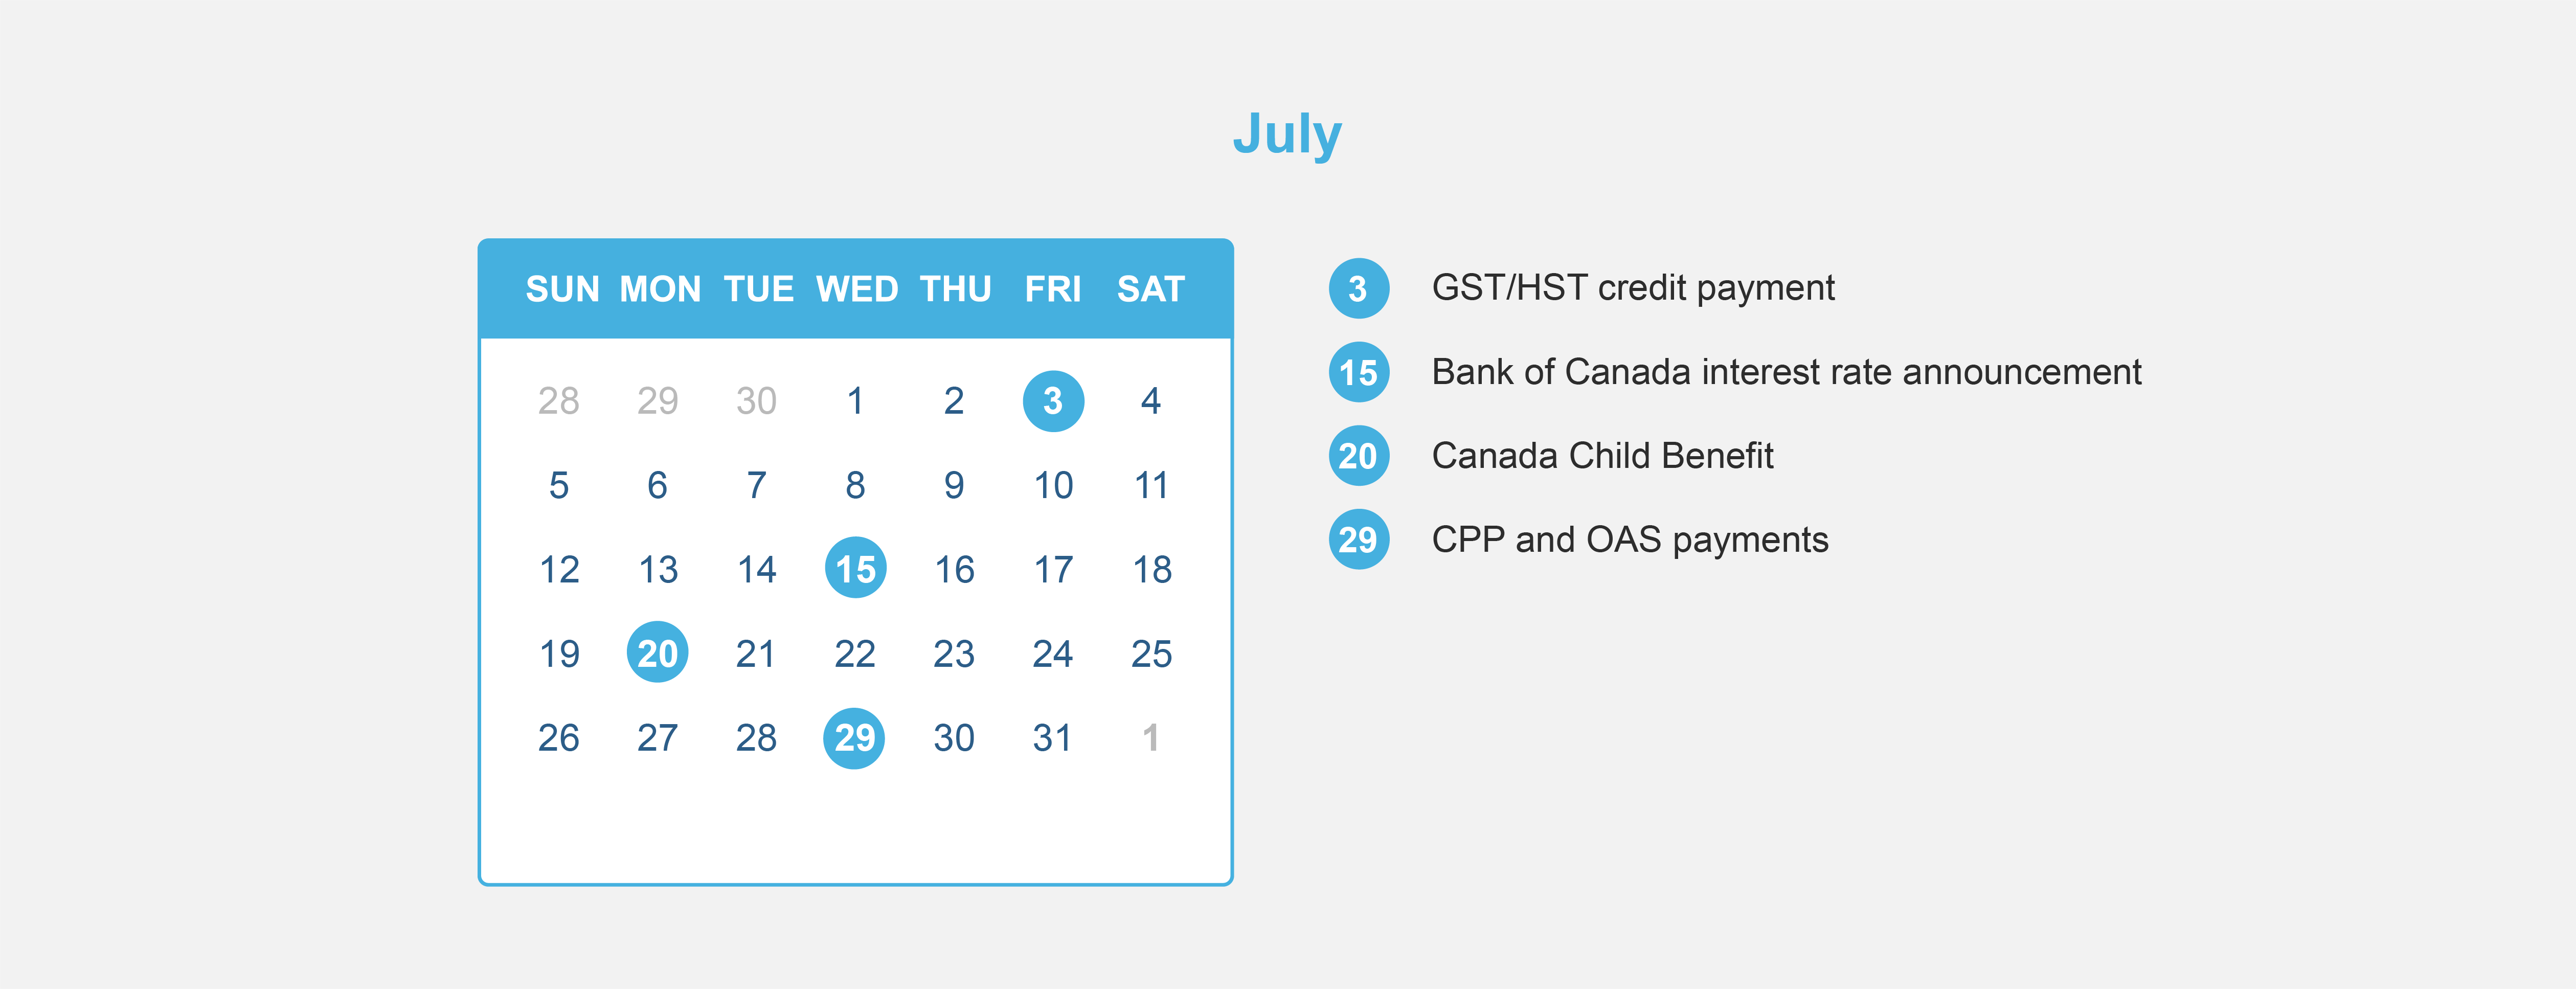
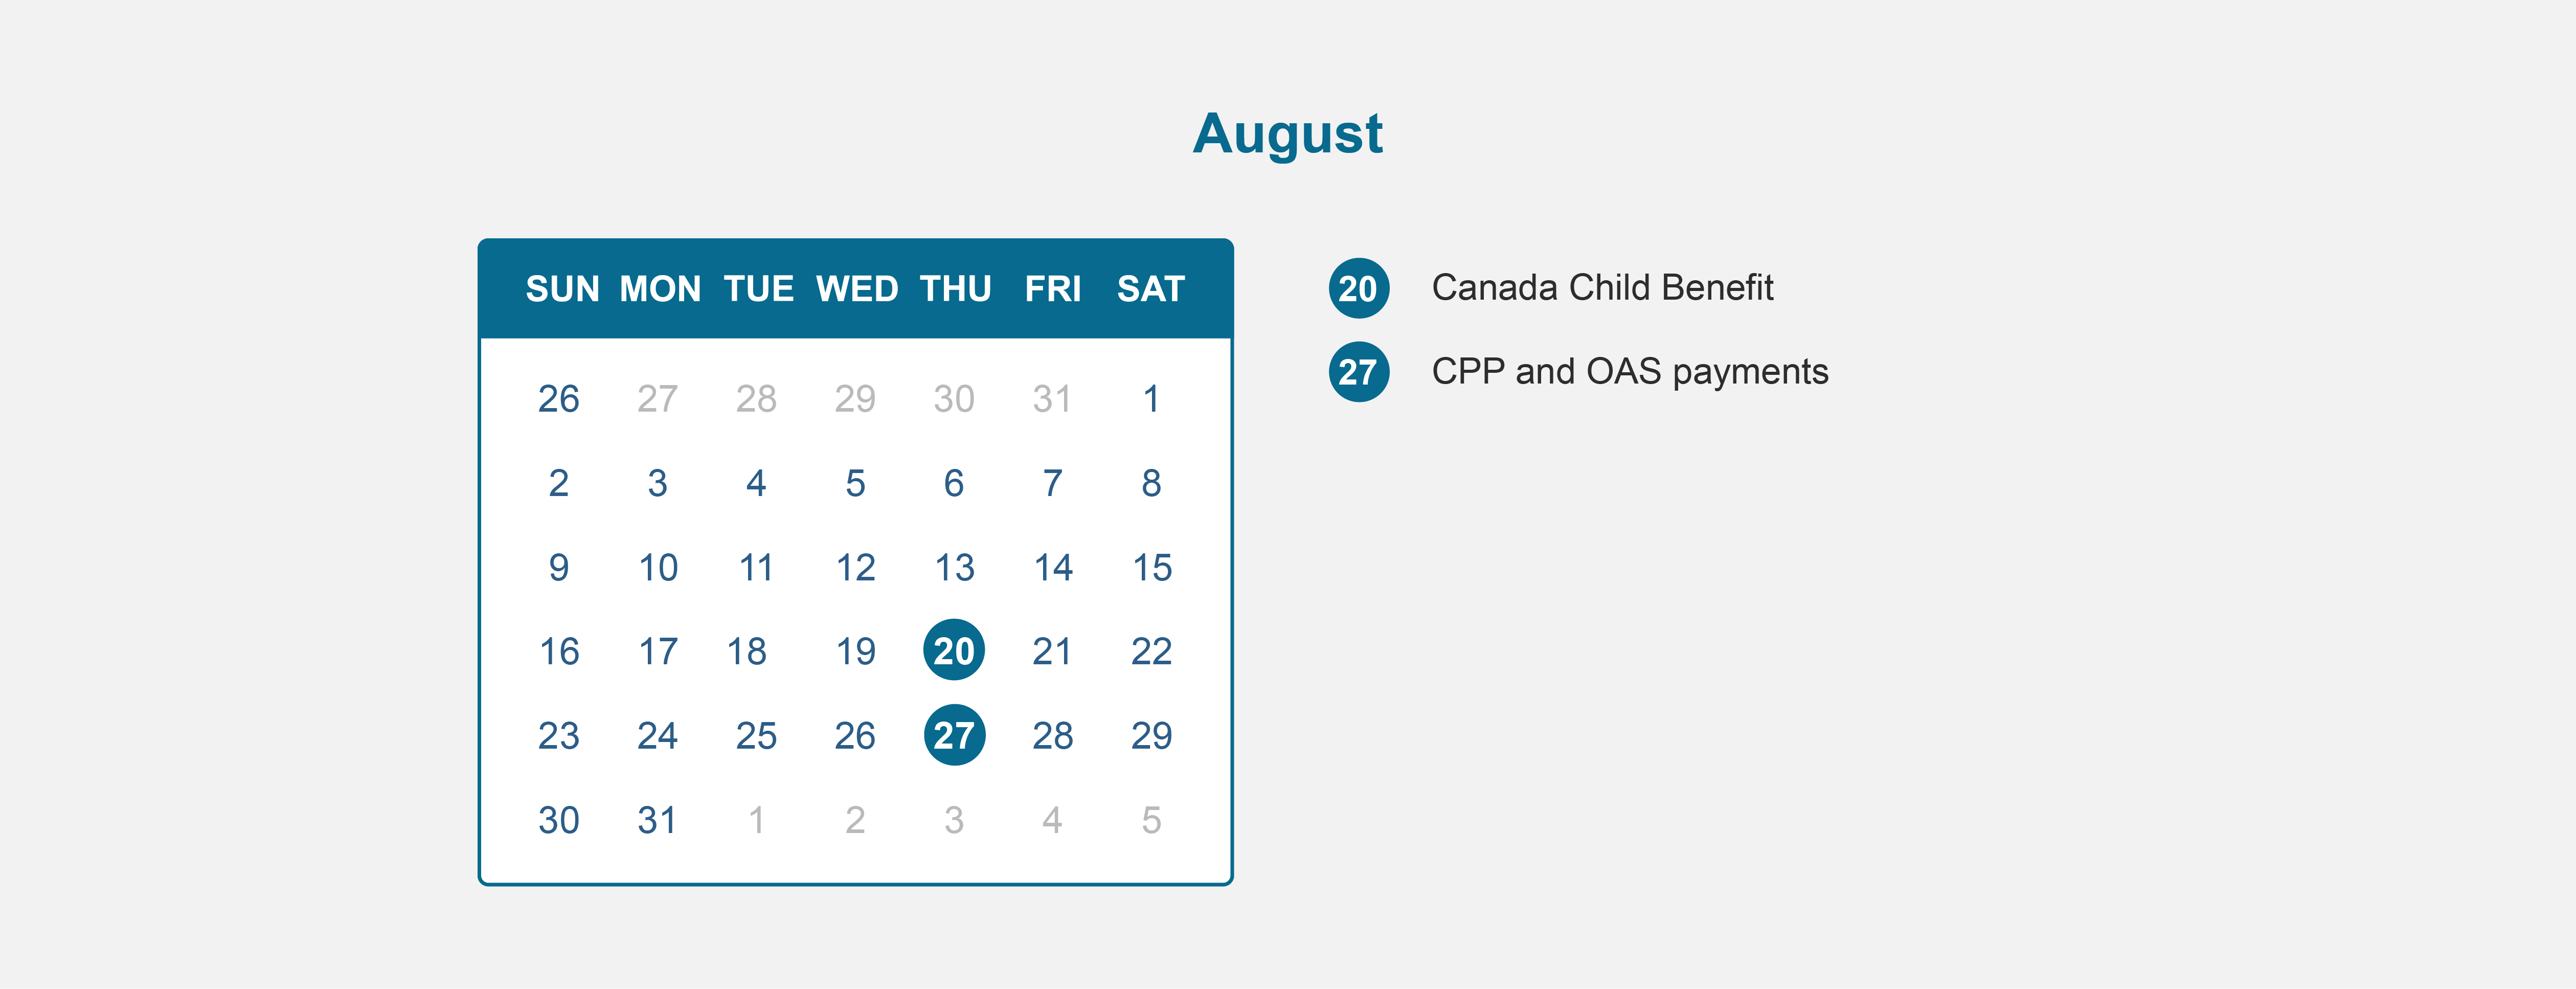
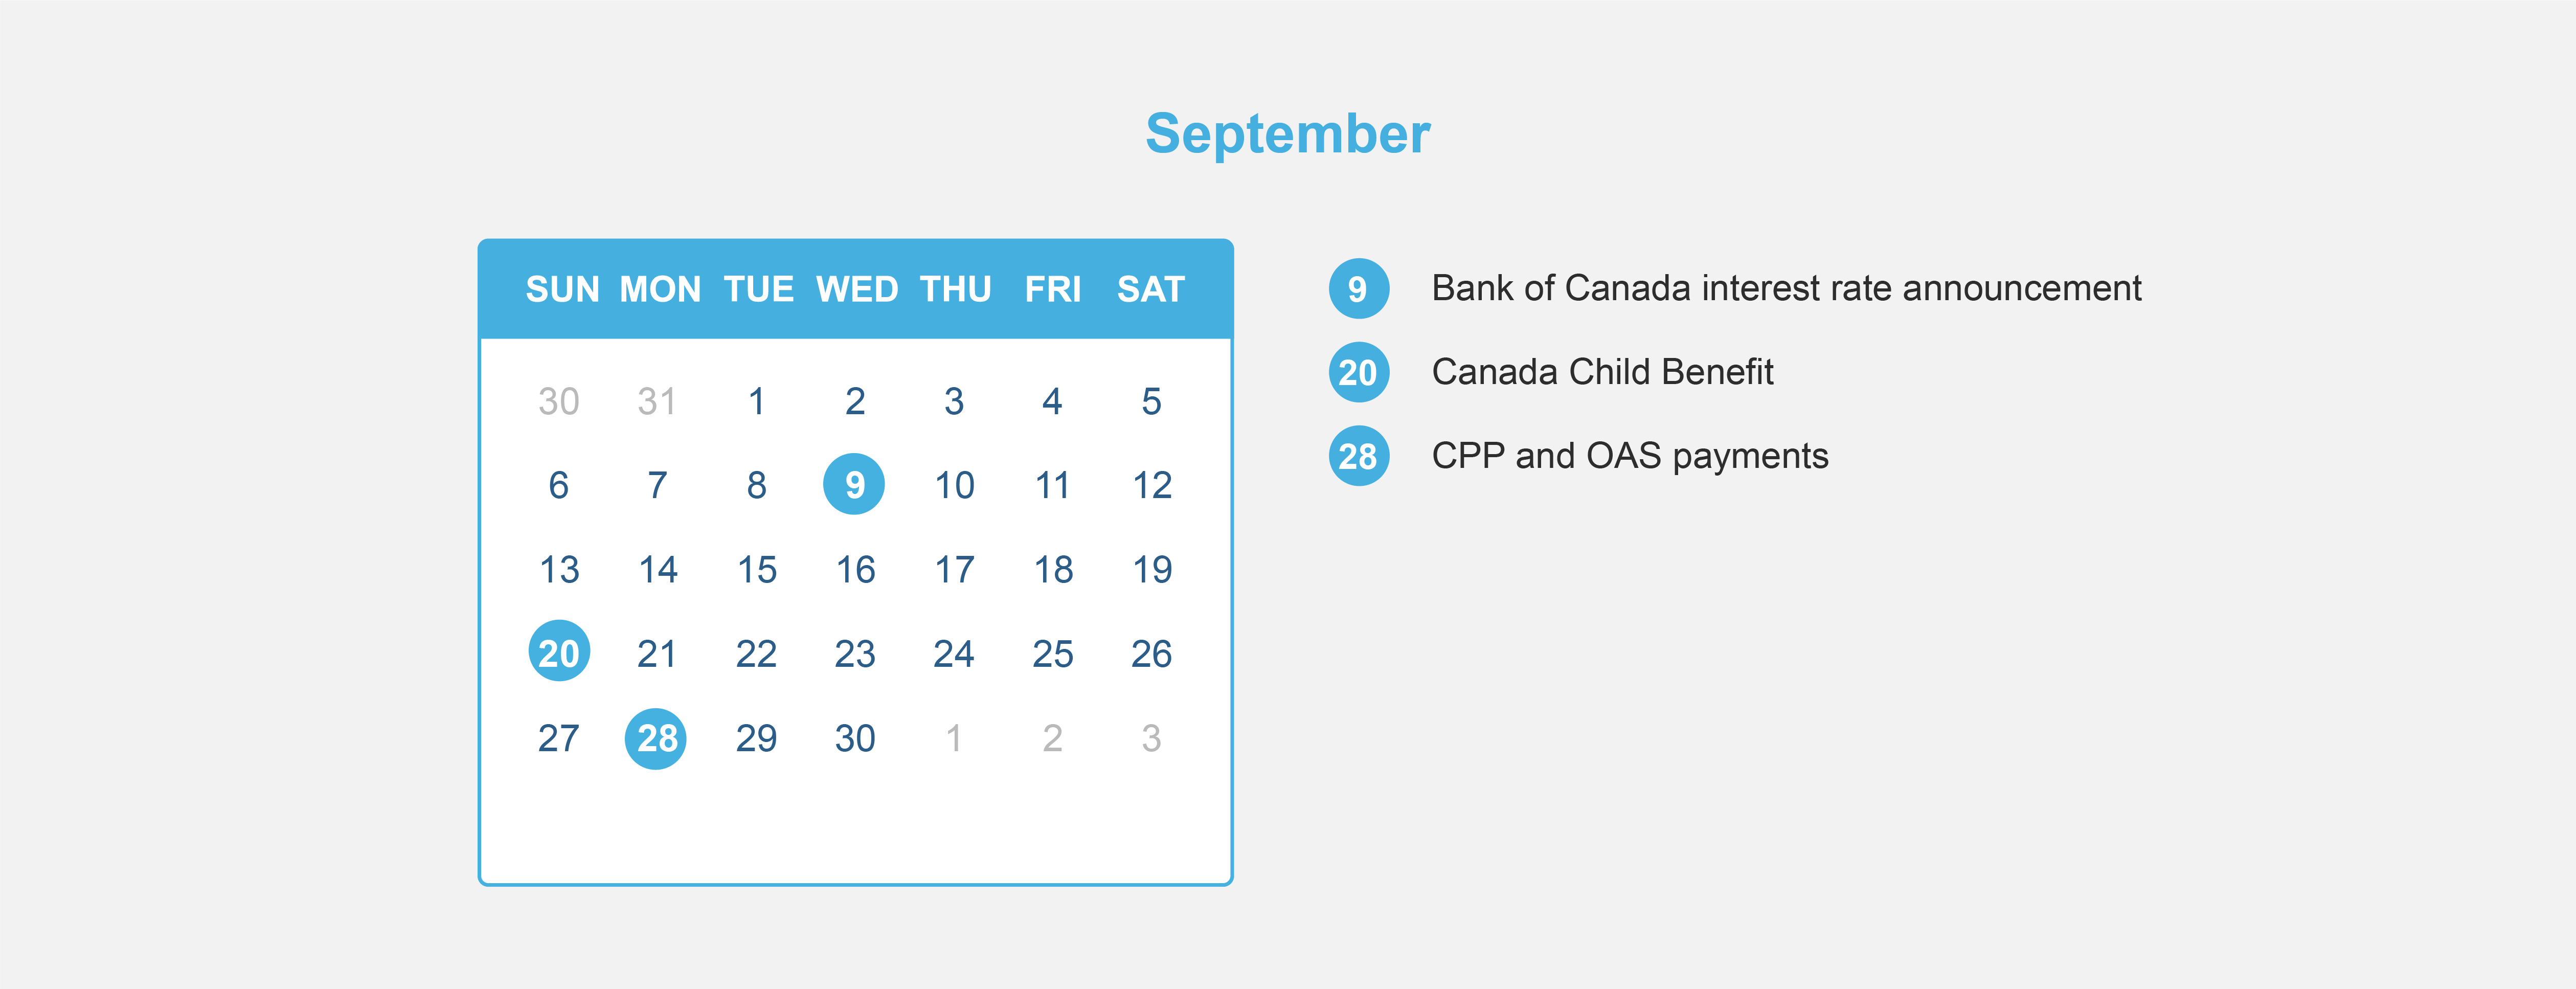
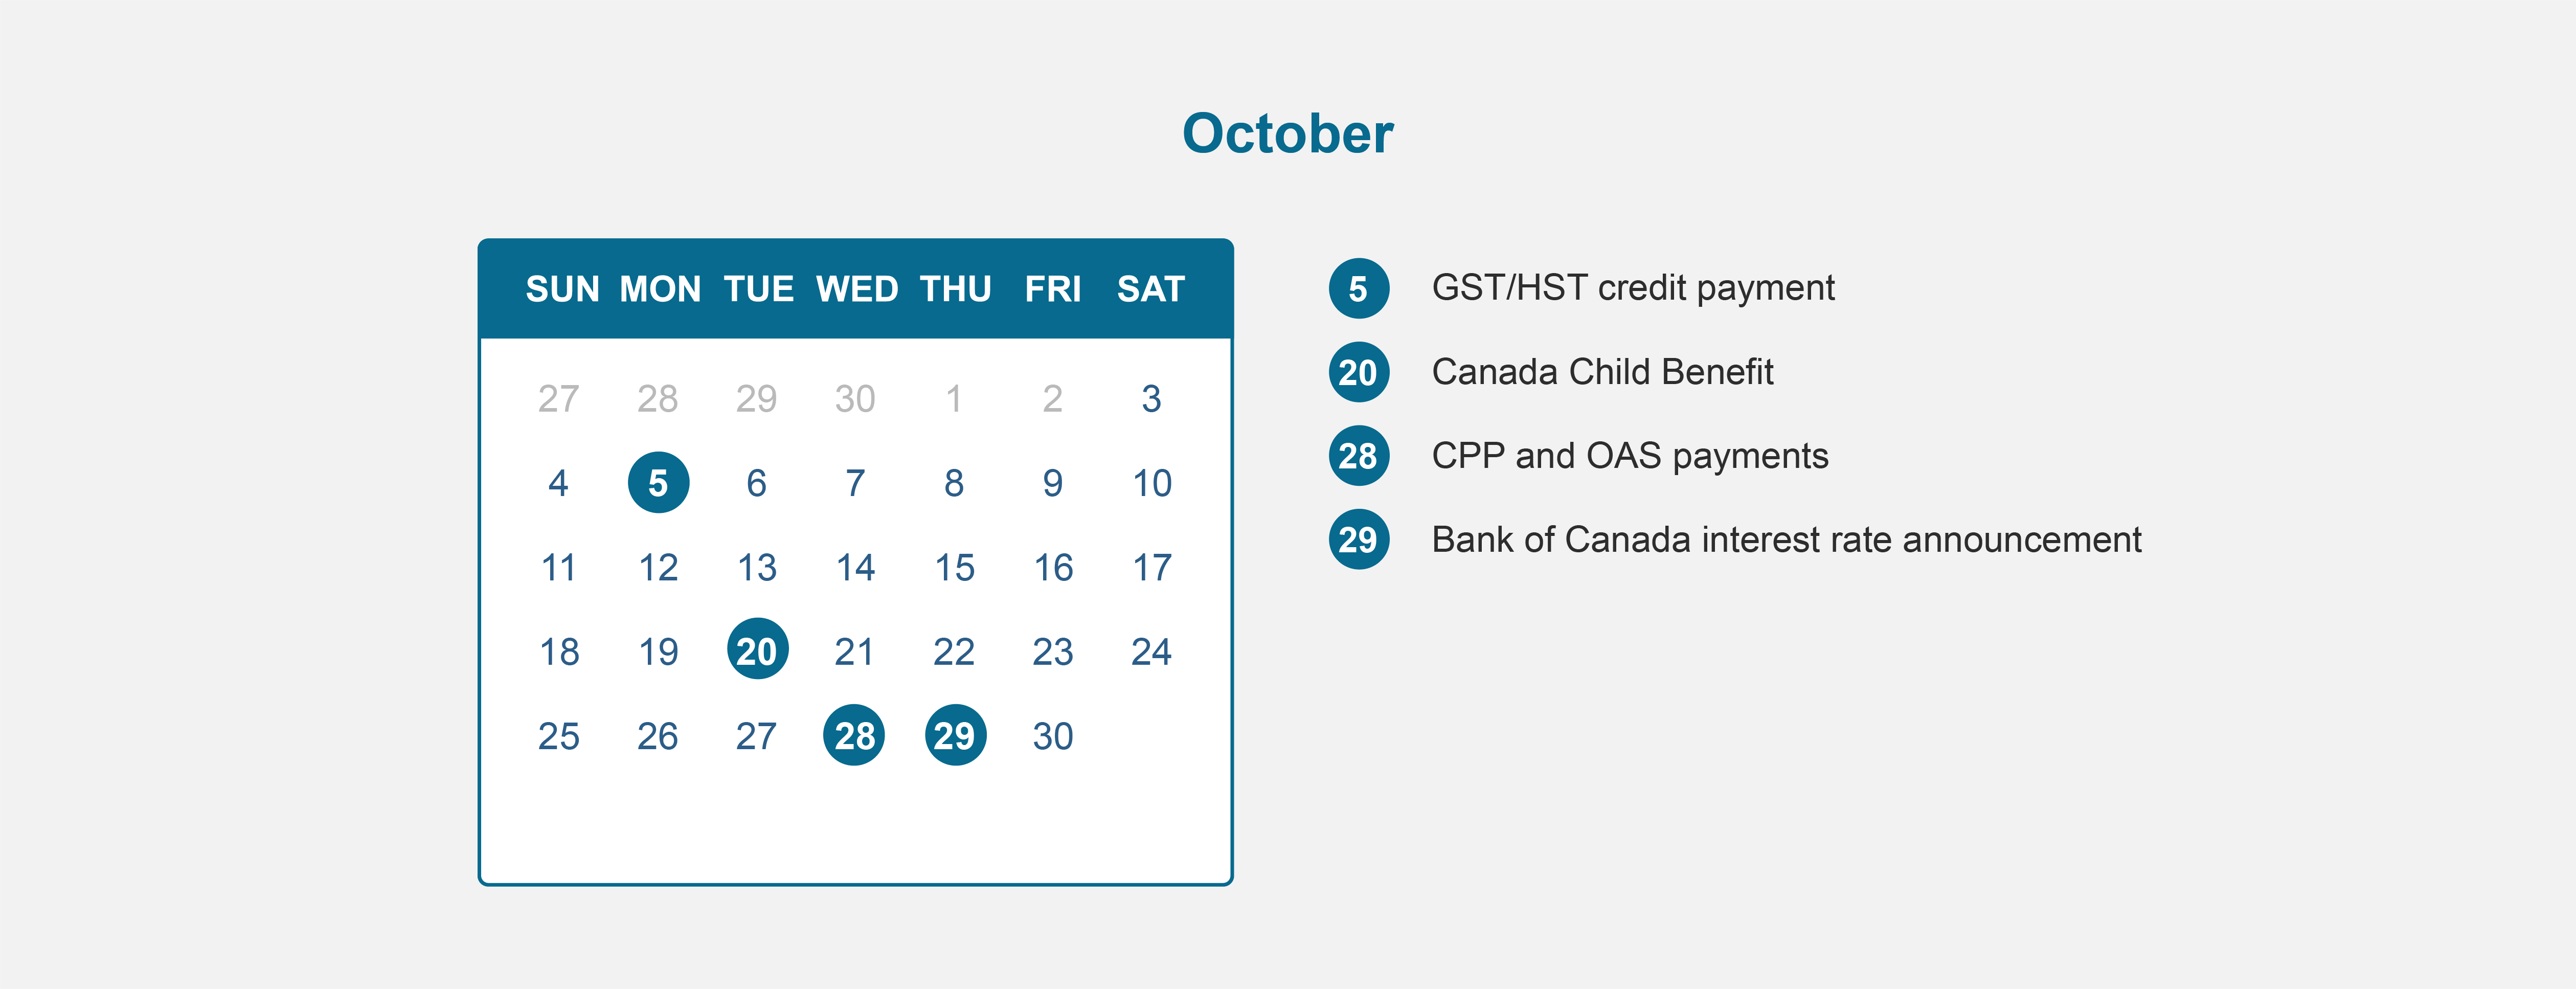
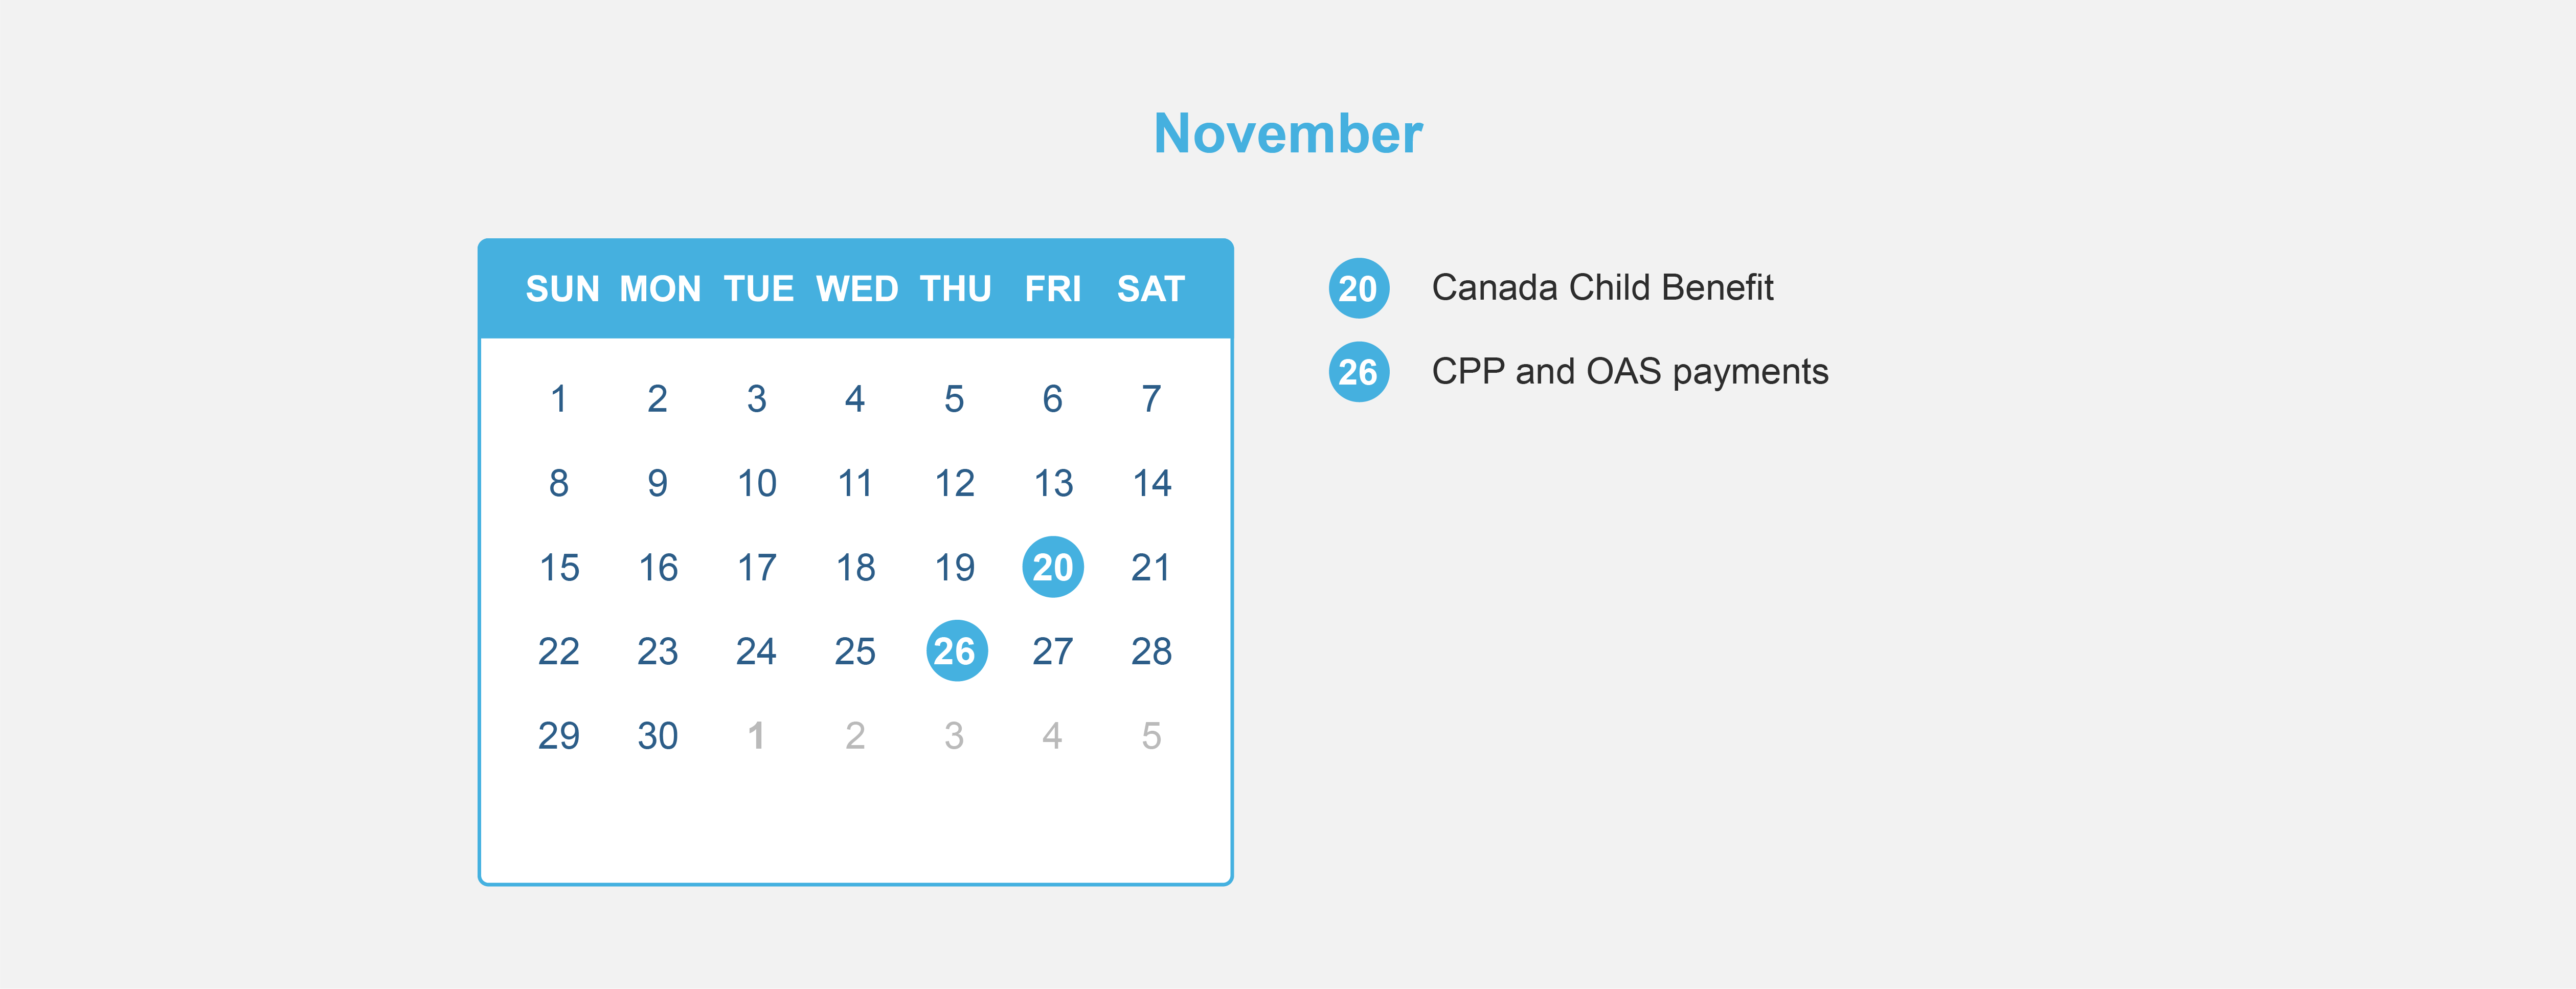
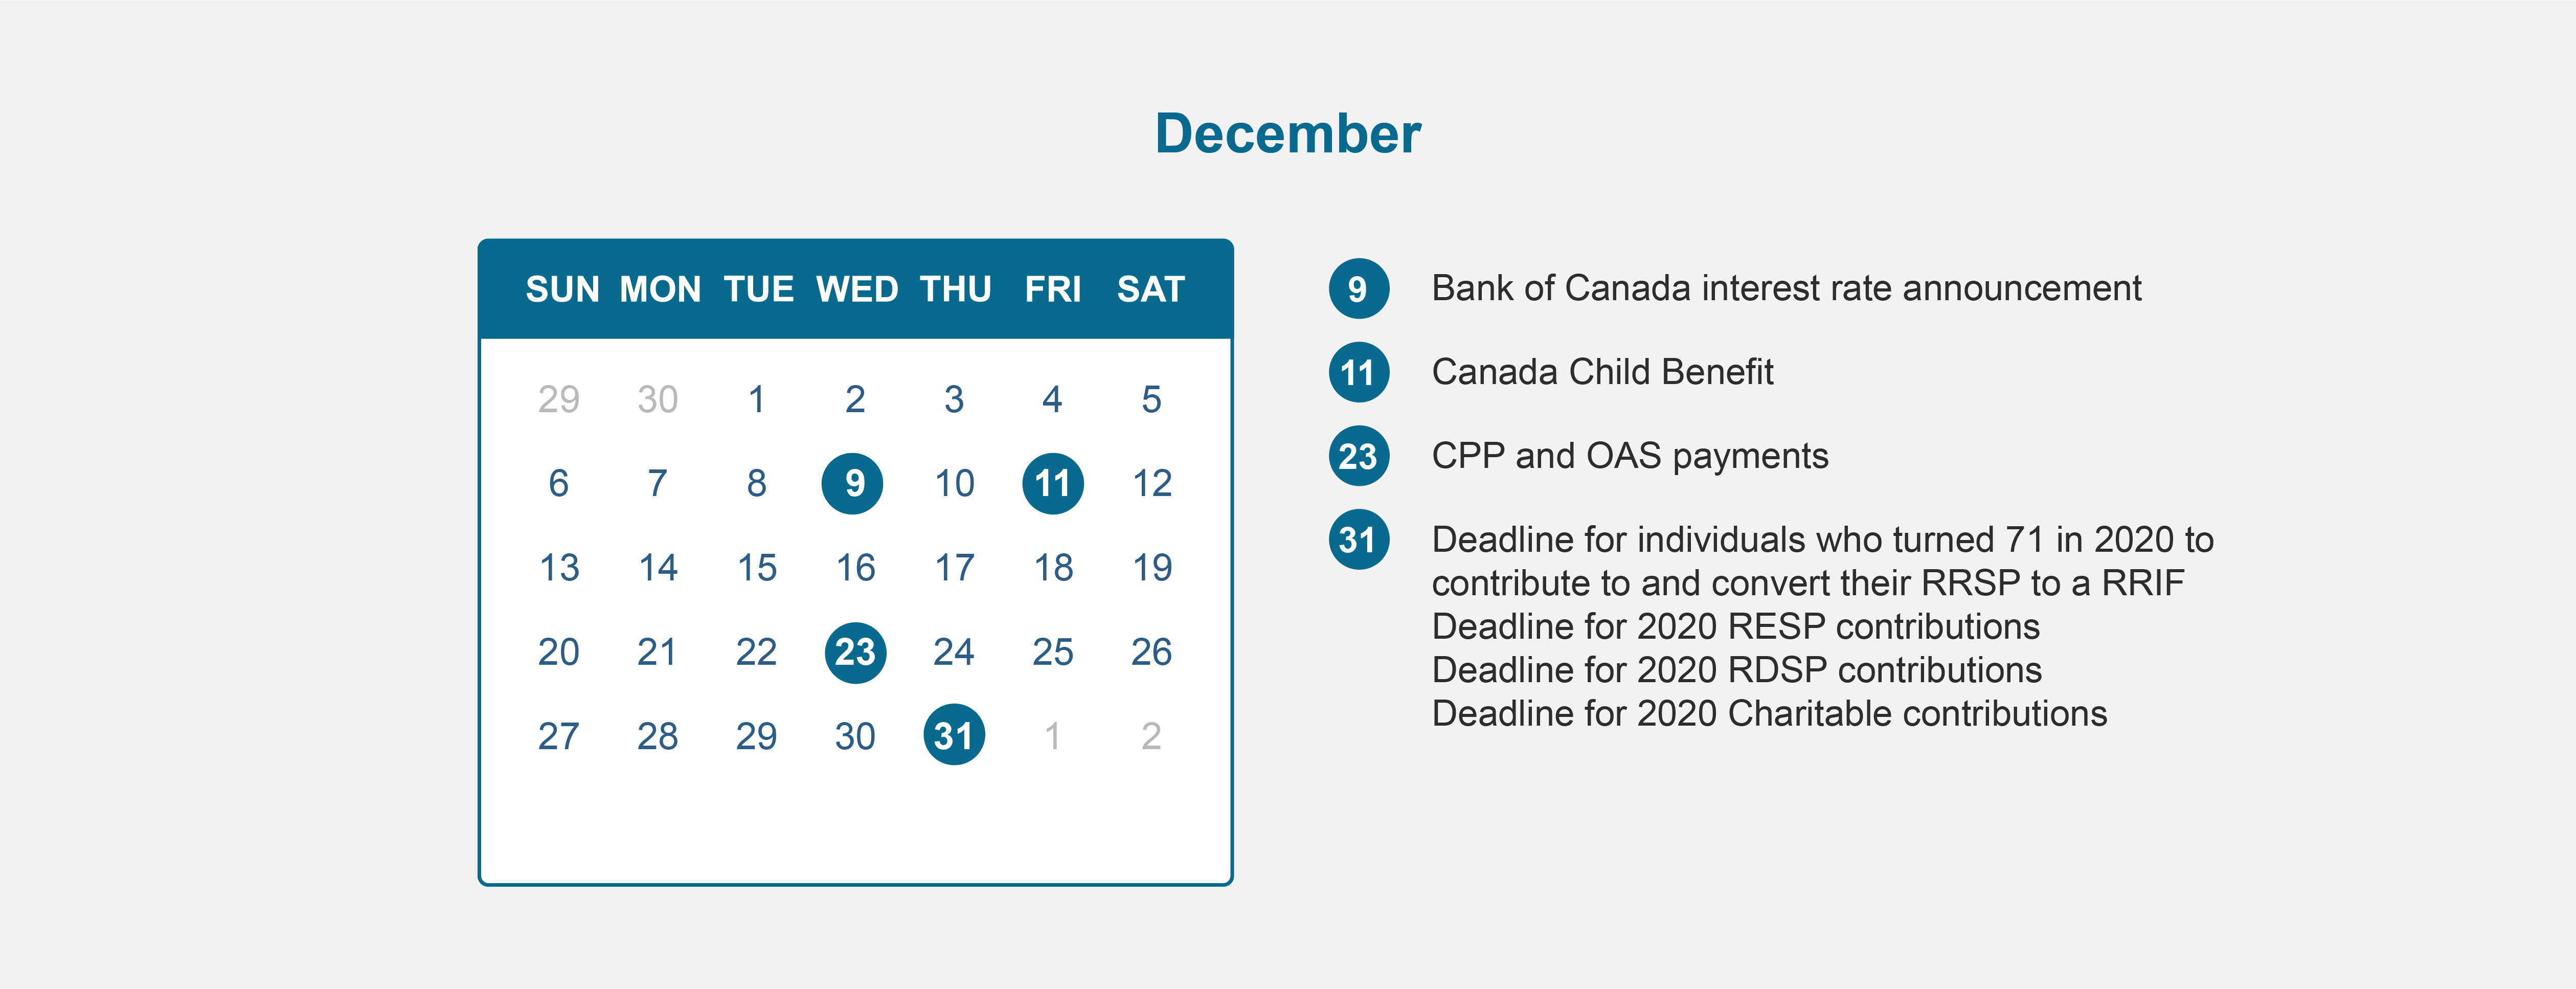
Financial Calendar for 2020 – All the dates you need to know to maximize your benefits!
Now that we are nearing year end, it’s a good time to review your finances. With the federal election over and no major tax personal tax changes for this year, 2019 is a good year to make sure you are effectively tax planning. Below, we have listed some of the key areas to consider and provided you with some useful guidelines to make sure that you cover all of the essentials. We have divided our tax planning tips into 4 sections:
Tax deadlines
Family tax issues
Managing your investments
Retirement planning
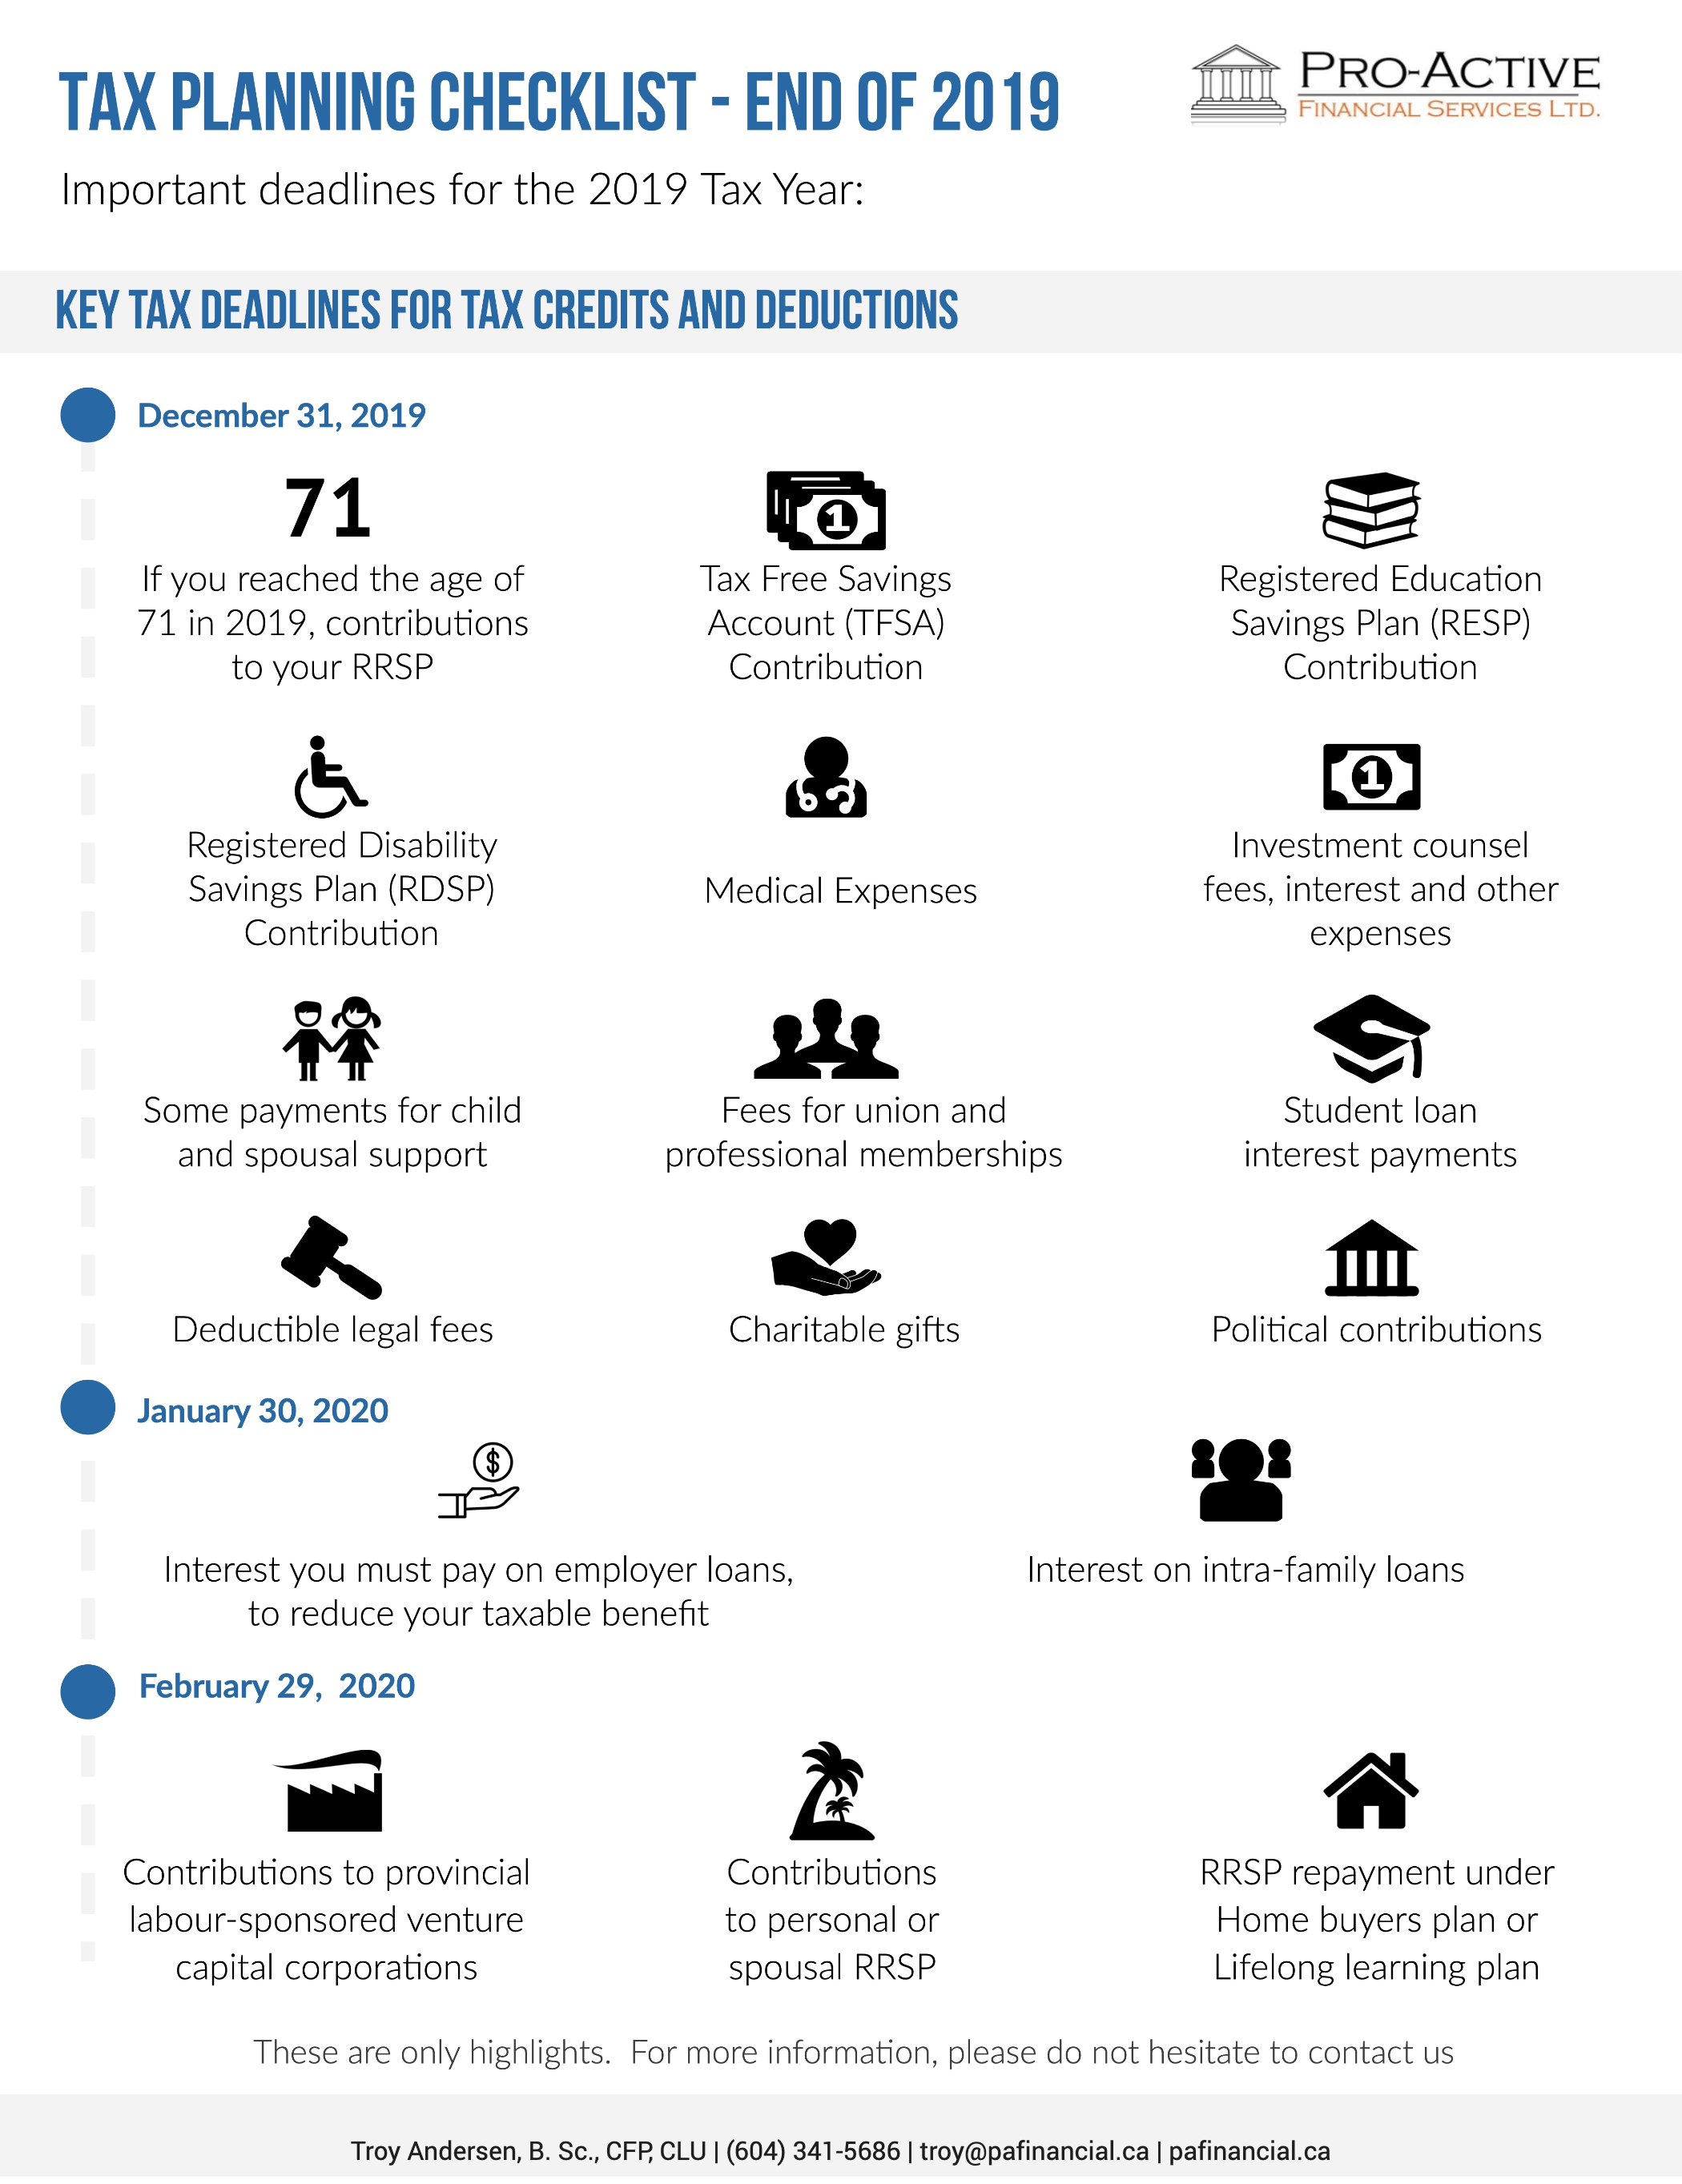
If you reached the age of 71 in 2019, contributions to your RRSP
Use up your TFSA contribution room
Contribute to RESP to get the Canadian education savings grant and the income-tested Canada learning bond.
Contribute to RDSP to get the Canada disability savings grant and the income-tested Canada disability savings bond.
Medical expenses
Investment counsel fees, interest and other expenses relating to investments
Some payments for child and spousal support
Fees for union and professional memberships
Student loan interest payments
Deductible legal fees
Charitable gifts
Political contributions
Interest on intra-family loans
Interest you must pay on employer loans, to reduce your taxable benefit
Contributions to provincial labour-sponsored venture capital corporations
Deductible contributions to a personal or spousal RRSP
RRSP Repayment under Home Buyers Plan or Lifelong Learning Plan
Check your eligibility to the Canada Child Benefit
In order to receive the Canada Child Benefit in 2020/21, you need to file your tax returns for 2019 because the benefit is calculated using the family income from the previous year. Eligibility depends on set criteria such as your family’s income and the number and age of your children and you may qualify for full or partial amount.
Consider family income splitting
The CRA offers a low interest rate on loans and it therefore makes sense to consider setting up an income splitting loan arrangements with members of your family, whereby you can potentially lock in the family loan at a low interest rate of 2% and subsequently invest the borrowed monies into a higher return investment and benefit from the lower tax status of your family member. Don’t forget to adhere to the Tax on Split Income rules.
Contribute to Registered Education Savings Plan (RESP)
The Registered Education Savings Plan (RESP) is a savings plan for parents and others to save for a child’s education. The Canada education savings grant (CESG) will match up to 20% of contributions up to $2,500. That means the CESG can add a maximum of $500 to an RESP each year. Grant room accumulates until the child turns 17, therefore unused basic CESG amounts for the current year are carried forward for possible use in the future years. The income-tested Canada learning bond (CLB) is paid directly to the RESP by the Canadian government to low-income families. There are no personal contributions required to receive the CLB.
Contribute to Registered Disability Savings Plan (RDSP)
The Registered Disability Savings Plan (RDSP) is a savings plan for parents and others to save for the financial security of a person who is eligible for the disability tax credit (DTC). The Canada disability savings grant will pay matching grants of 300%, 200% or 100% depending on the beneficiary’s adjusted family net income and amount contributed. The income-tested Canada disability savings bond is paid directly to the RDSP by the Canadian government to low- income Canadians with disabilities. Before December 31 of the year you turn 49 years old, you can carry forward up to 10 years of unused grant and bond entitlements to future years, as long as you met the eligibility requirements during the carry forward years.
Use up your TFSA contribution room
If you are able, it’s worth contributing the full $6,000 to your TFSA for 2019. You can also contribute more (up to $63,500) if you are 28 or older and haven’t made any previous TFSA contributions.
Contribute to Registered Education Savings Plan (RESP)
The Registered Education Savings Plan (RESP) is a savings plan for parents and others to save for a child’s education. The Canada education savings grant (CESG) will match up to 20% of contributions up to $2,500. That means the CESG can add a maximum of $500 to an RESP each year. Grant room accumulates until the child turns 17, therefore unused basic CESG amounts for the current year are carried forward for possible use in the future years. The income-tested Canada learning bond (CLB) is paid directly to the RESP by the Canadian government to low-income families. There are no personal contributions required to receive the CLB.
Contribute to Registered Disability Savings Plan (RDSP)
The Registered Disability Savings Plan (RDSP) is a savings plan for parents and others save for the financial security of a person who is eligible for the disability tax credit (DTC). The Canada disability savings grant will pay matching grants of 300%, 200% or 100% depending on the beneficiary’s adjusted family net income and amount contributed. The income-tested Canada disability savings bond is paid directly to the RDSP by the Canadian government to low- income Canadians with disabilities. Before December 31 of the year you turn 49 years old, you can carry forward up to 10 years of unused grant and bond entitlements to future years, as long as you met the eligibility requirements during the carry forward years.
Donate securities to charity
Make a donation by year end will provide you tax savings. If you donate eligible securities or mutual funds, capital gains tax does not apply, and you can receive a tax receipt for their full market value. Also, the charity gets the full value of the securities.
Think about selling any investments with unrealized capital losses
It might be worth doing this before year-end in order to apply the loss against any net capital gains achieved during the last three years. Any late trades should ideally be completed on or prior to December 24, 2019 and subsequently confirmed with your broker.
Conversely, if you have investments with unrealized capital gains which are not able to be offset with capital losses, it may be worth selling them after 2019 in order to be taxed on the income the following year.
Consider the timing of purchasing of certain non-registered investments
If you are considering purchasing an interest-bearing investment like a guaranteed investment certificate (GIC) with a maturity date of one year or more, you may consider delaying the purchase to the following year, so you don’t have to pay tax on accrued interest until 2021. You should also consider this with mutual funds that make taxable distributions before the end of 2019, consider delaying this until early 2020. Don’t pay taxes earlier than necessary.
Check if you have investments in a corporation
The new passive investment income rules apply to tax years from 2018. They state that the small business deduction is reduced for companies which are affected with between $50,000 and $150,000 of investment income, therefore the small business deduction has been stopped completely for corporations which earn passive investment income of more than $150,000. At a provincial level, Ontario and New Brunswick have indicated that they are not following the federal rules to limit access to the small business deduction.
Make the most of your RRSP
The deadline for making contributions to your RRSP for the year 2019 is February 29, 2020. There are three things that affect how much you may contribution towards your RRSP, as follows:
18% of your previous year’s earned income
Up to a maximum of $26,500 for 2019 and $27,230 for 2020
Your pension adjustment
Remember that deducting your RRSP contribution reduces your after-tax cost of making said contribution.
Check when your RRSP is due to end
You should wind-up your RRSP if you reached the age of 71 during 2019 and your final contributions should be made by December 31, 2019.
Convert to RRIF before year end
If you’re 65 or older in the year, you’re entitled to a pension credit that can fully or partly offset the tax on the first $2,000 of eligible income annually. Consider setting up a RRIF before year-end to pay out $2,000 annually if you don’t have any other eligible pension income.
Contact us if you have any questions, we can help.
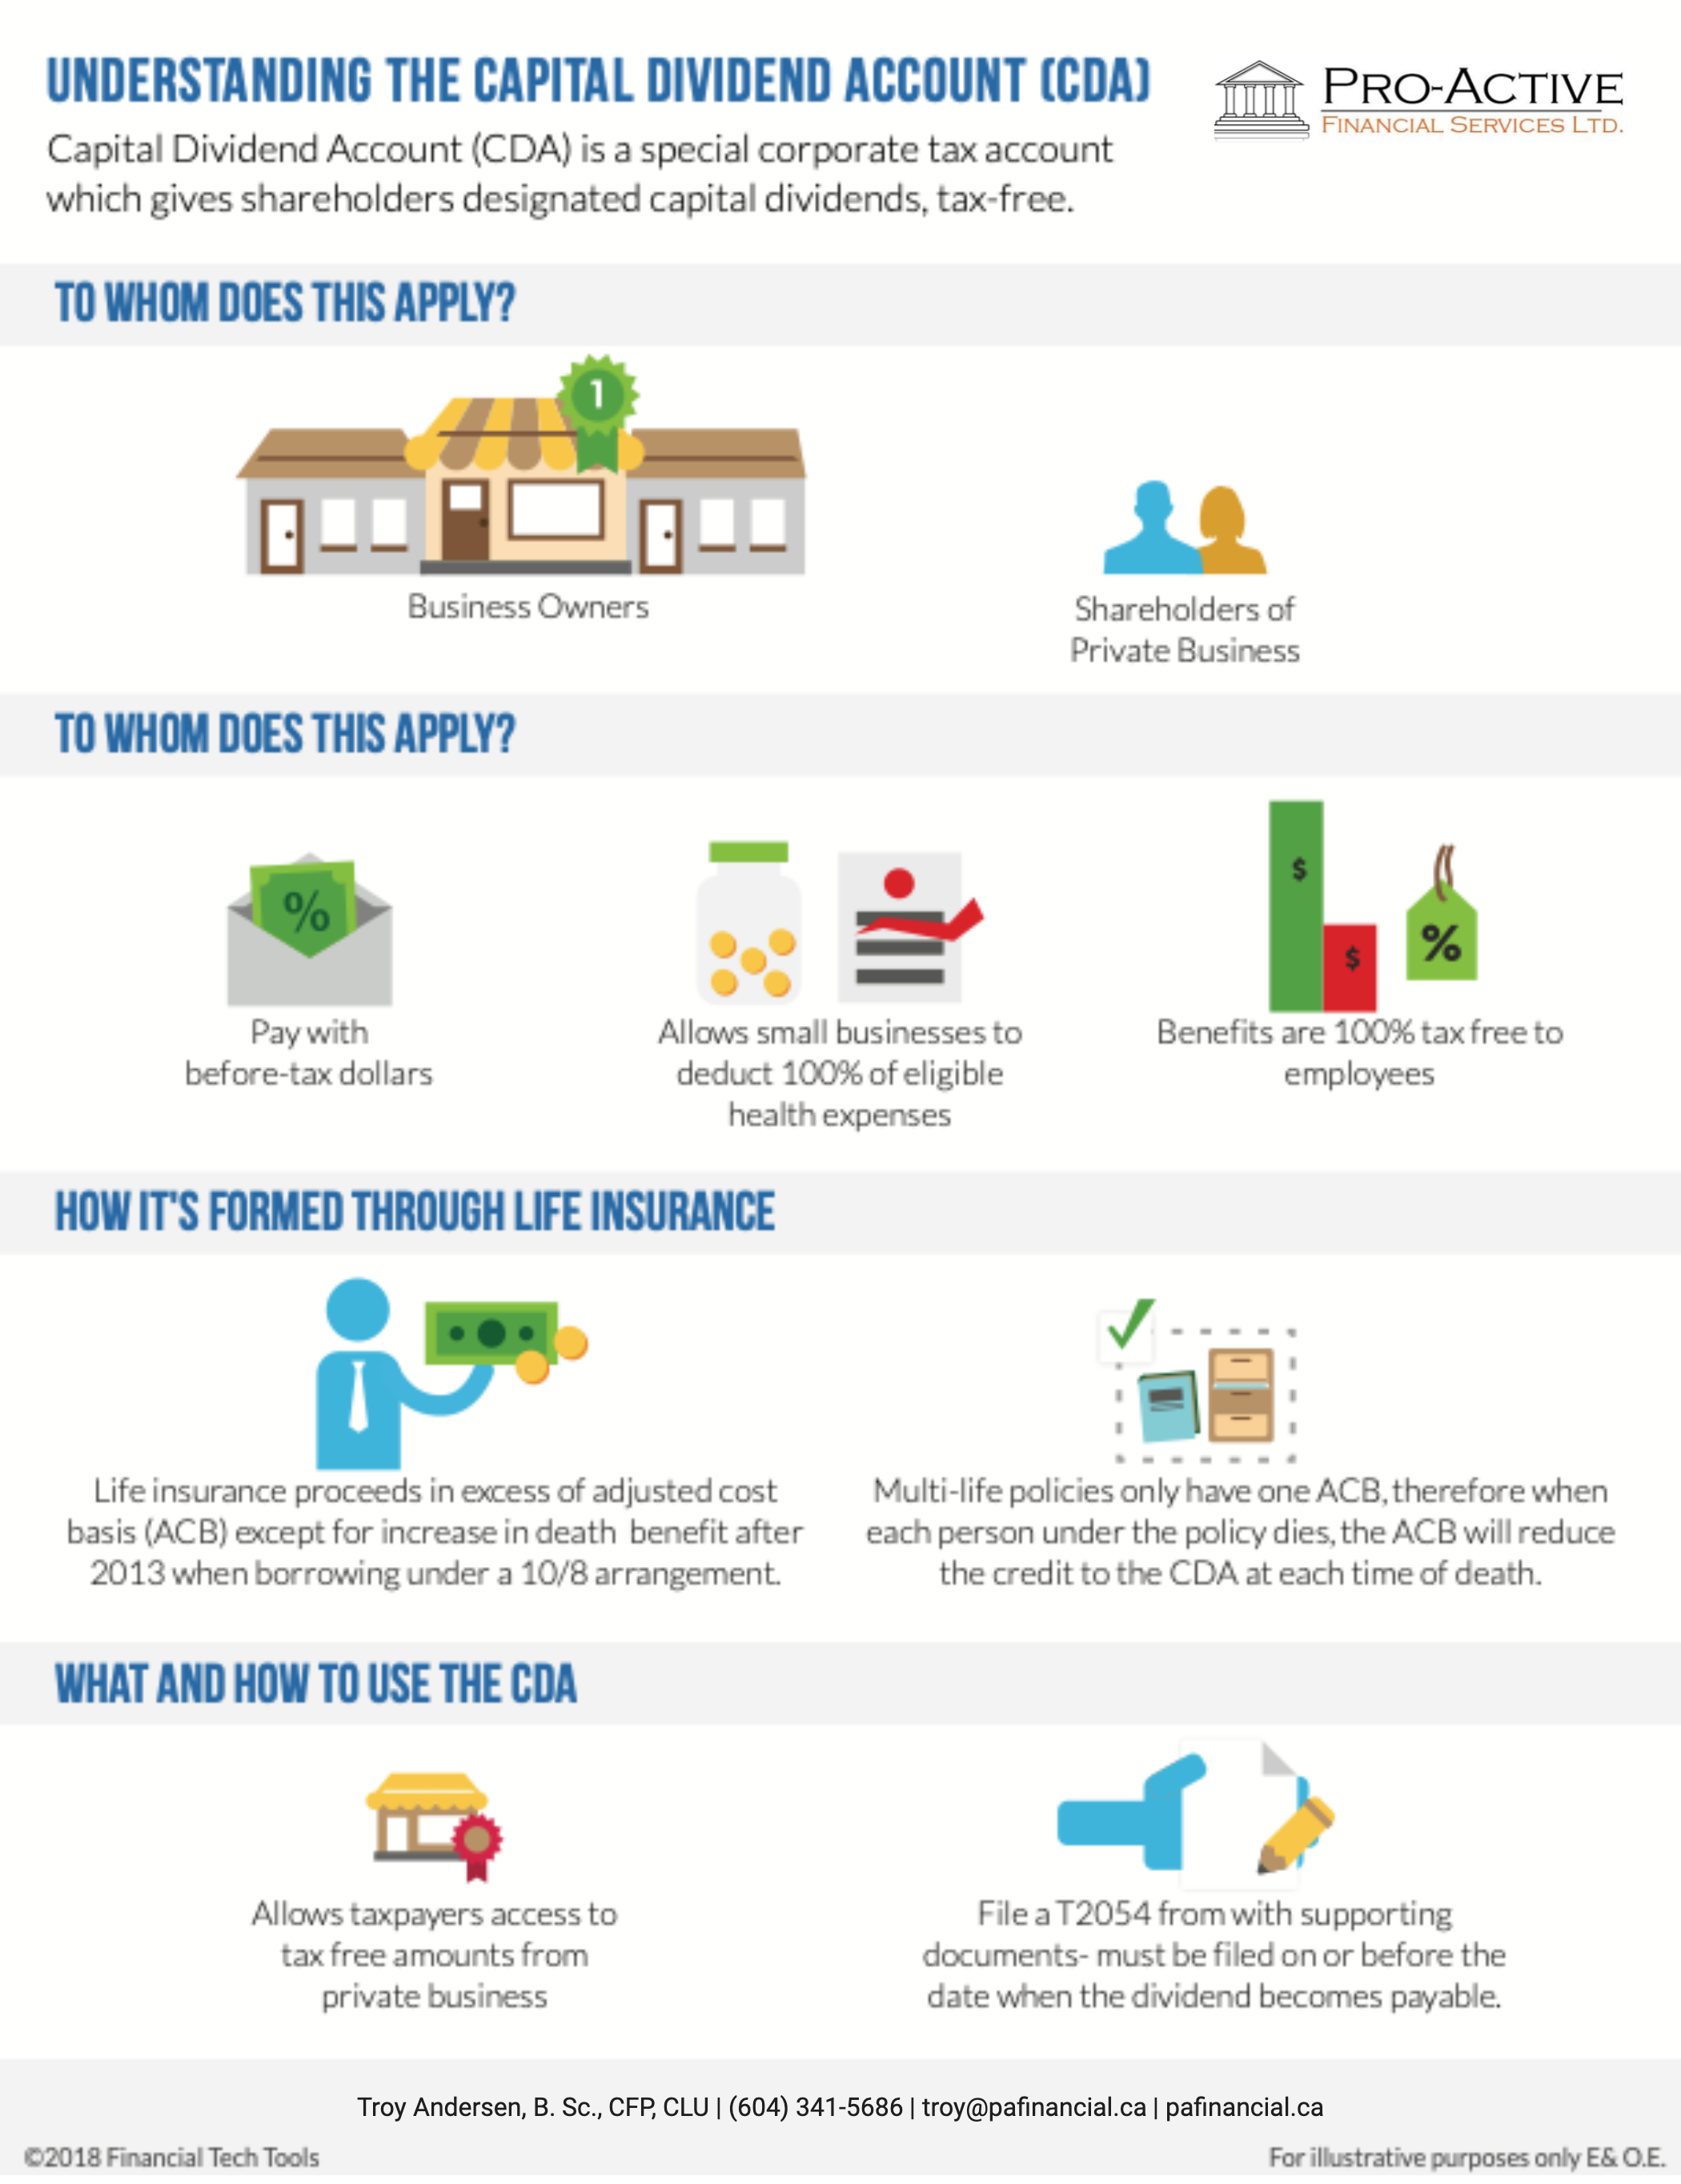
Capital Dividend Account (CDA) is a special corporate tax account which gives shareholders designated capital dividends, tax-free. This account is not recorded in the corporation’s taxable accounting entries or financial statements. For this type of account, capital dividend is taken out from paid-in capital and not from retained earnings.
Business Owners
Shareholders of Private Business
Life insurance proceeds in excess of adjusted cost basis “(ACB)” “except” for increase in death benefit after 2013 when borrowing under a 10/8 arrangement.
Multi-life policies only have one ACB, therefore when each person under the policy dies, the ACB will reduce the credit to the CDA at each time of death.
When capital dividends are paid out to shareholders, these are not taxable. The Capital Dividend Account is part of a tax provision whose goal it is to enable tax-free money received by a company, to then be given to its shareholders, tax free. Therefore, shareholders are not required to pay taxes on these distributions.
The CDA can be complicated, please talk to us to see if this makes sense for your clients.
Many business owners have built up earnings in their corporation and are looking for tax efficient ways to pull the earnings out to achieve their personal and business financial goals such as:
building and protecting your savings
providing for loved ones
planning for retirement
What’s the purpose of the investment? First, think about what you’ll be doing with your savings. This will help dictate what savings vehicle is best suited for your situation. Then consider the following factors:
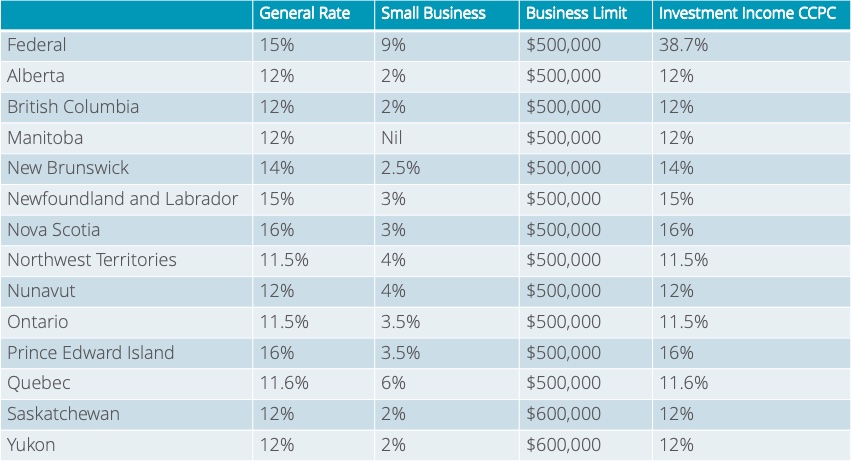
Taxes: As a small business owner, you have access to the small business tax rate which is typically lower than your personal tax rate. (See table below.) Also, as of January 1, 2019, the Federal Budget decreased the small business limit for corporations with a set threshold of income generated from passive investments.
2019 Corporate Income Tax Rates
Timing: You can control the timing of the payout which means you could potentially defer paying out the money until you need it and determine if you’d like to pay it out as salary or dividend.
Creditor Protection: Sometimes, investments held inside a corporation can be vulnerable to creditors, therefore you may want to consider using a holding company or trust or pay out money to yourself personally. This can be complex and requires professional advice.
Capital Gains Exemption: If your investment grows too large, it may endanger your qualification for the lifetime capital gains exemption that ‘s available when shares of a qualified small business corporation are sold or transferred.
For business owners, before investing personally or corporately, it’s certainly worth seeking professional advice to ensure that it suits your individual circumstances.
One of the age-old financial quandaries asked of financial advisors is “shall I invest in property or funds?”. Predictably, the answer is not at all straightforward and depends on many factors, including your own financial style, personality and circumstances. Let’s take a look at the pros and cons of each choice to help you to be better informed about which could be the most lucrative option for you:
Benefits of investing in funds
It’s all too easy to go along with the generally-accepted myth that investing in property is a sure-fire way to secure your financial future. After all, house prices have appreciated in general terms for several years now and have become a very popular way for young people to invest for the future – this could also be, in part, down to the fact that their parents have benefited from the property booms of the past and made their own money this way, therefore presume the same will work for their children.
It’s fair to say, then, that investing the stock market is a much less common and popular way for people to invest their money. Despite market crashes, long term fund ownership is hands down the greatest creator of wealth in history and high quality funds generally not only increase their profits every year but also pay out increased cash dividends too.
Other advantages of fund ownership include the fact that you can diversify your portfolio easily, borrow against your funds easily and also benefit from the fact that funds are much more liquid than real estate, giving you maximum financial flexibility.
So, why do fewer people invest in funds than real estate?
It could be due to the two market crashes that have occurred since 2000, making people wary of getting involved in what they perhaps see as a complex and inherently risky way to make money. Many fail to take the long-term view of funds and the fact that, to financially benefit in the best way, you need to ride the highs and lows for a number of years to get a good return on your initial investment.
Another reason could be the fact that many people underestimate the real cost of home ownership. Additional costs such as maintenance, insurance and mortgage interest must be factored into investment calculations but are often not, making property a seemingly more attractive investment option.
Drawbacks of investing in funds
You really have to be in this game for the long term to see your money grow consistently and many people don’t have the discipline or patience to hold their nerve and keep their money in the same place for a prolonged period. This can often result in cashing in one’s funds too early and missing out on long term benefits. Similarly, because the prices of funds can fluctuate so much, many are too nervous about investing and don’t see the opportunities to purchase more funds at reduced prices to benefit them in the long term.
Benefits of investing in real estate
Many individuals in their twenties and thirties who are just starting out thinking about how best to secure their financial future feel more comfortable with investing in property and the notion of “owning one’s own home” – likely brought about by their parents’ influence, as discussed above. They perhaps feel more confident in the process, terminology and philosophy of real estate and believe that they are more likely to succeed in this area.
Another benefit could be the fact that, by purchasing a property, you feel that you own something tangible, as opposed to the money invested in funds and shares which could be said to exist only online or on paper.
Finally, many take comfort from the fact that it is potentially harder to be defrauded in relation to real estate as there are so many varied, physical checks that one can perform to verify the facts, such as property inspections, tenant background checks etc, whereas with funds, a lot of trust has to be given to the management company or auditors.
Drawbacks of investing in real estate
There are a number of hidden costs to real estate, particularly if your property is unoccupied for a period of time and you are still liable to pay taxes, maintenance etc. It’s also true that the maintenance of a property can be a time consuming as well as an expensive business, due to the requirement to deal with routine as well as emergency issues.
What’s more, it’s true that the actual value of real estate hardly ever increases in inflation-adjusted terms, therefore the returns can be healthy but the true value of the property doesn’t actually change. It’s due to this that many feel that investing in funds is a much more solid and lucrative way to receive good returns.
Talk to us, we can help you determine what works best for you.
The 2019 budget is titled “Investing in the Middle Class. Here are the highlights from the 2019 Federal Budget.
We’ve put together the key measures for:
Individuals and Families
Business Owners and Executives
Retirement and Retirees
Farmers and Fishers
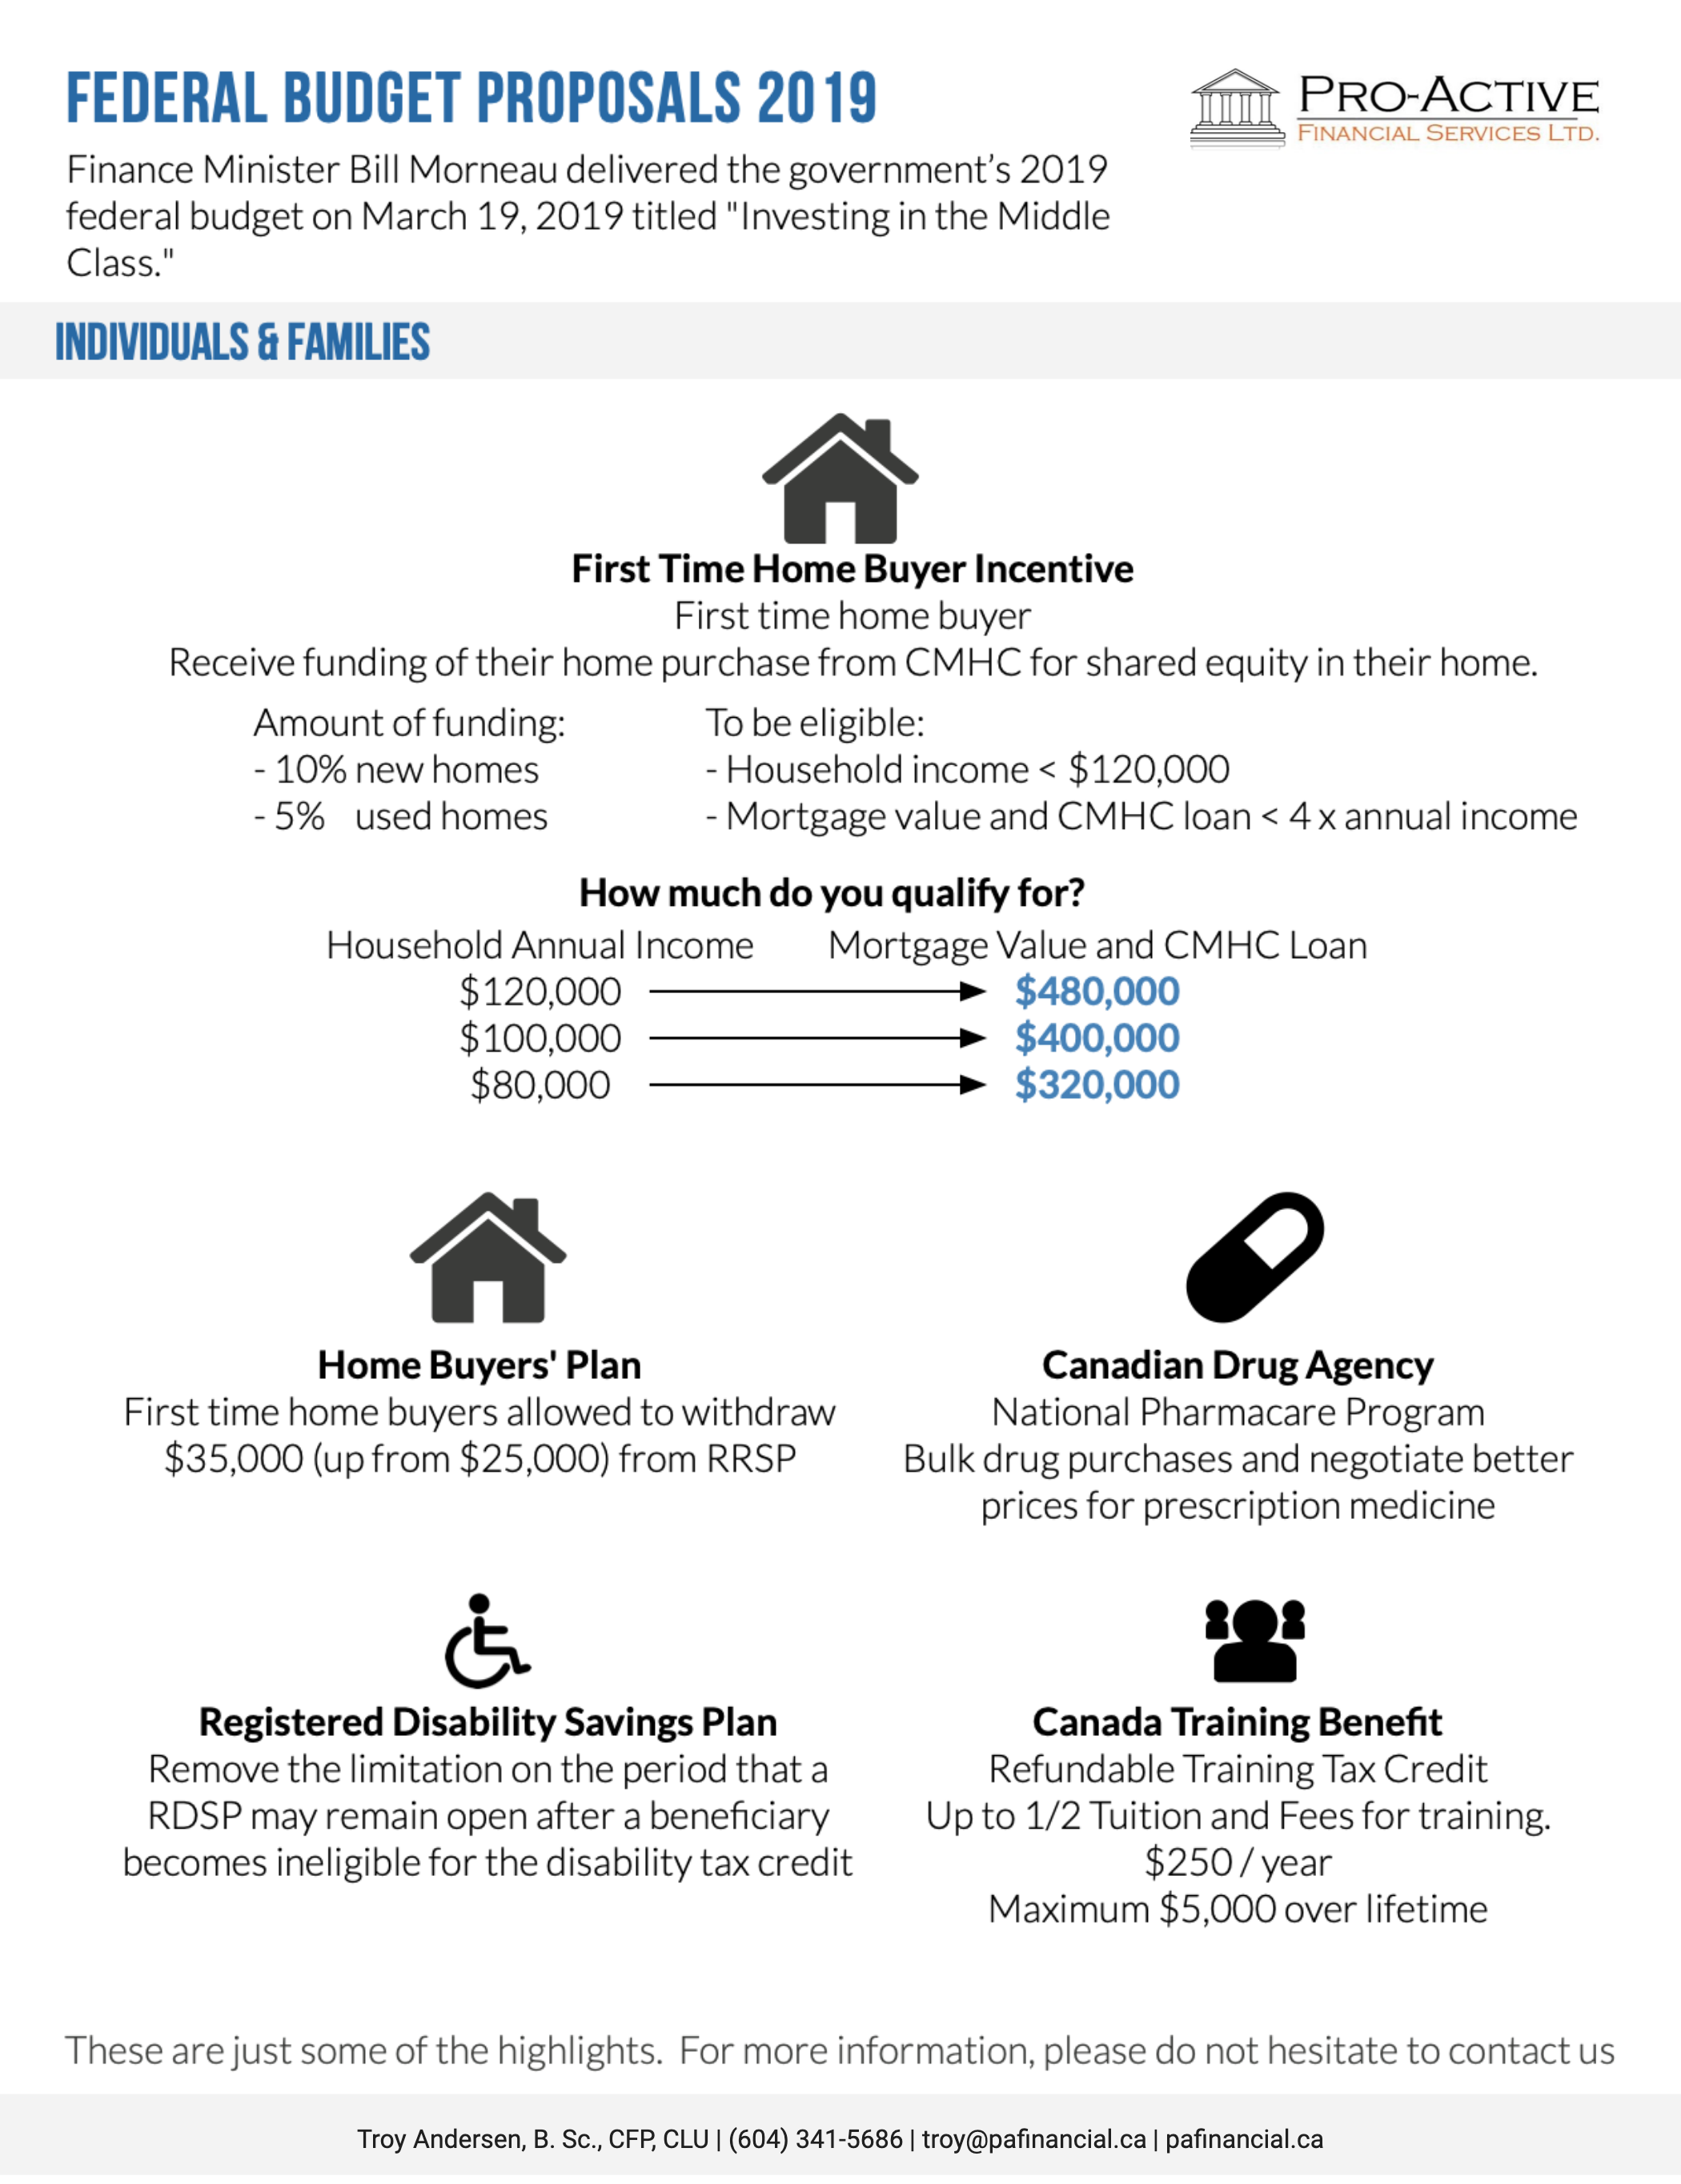
Home Buyers’ Plan
Currently, the Home Buyers’ Plan allows first time home buyers to withdraw $25,000 from their Registered Retirement Savings Plan (RRSP), the budget proposes an increase this to $35,000.
First Time Home Buyer Incentive
The Incentive is to provide eligible first-time home buyers with shared equity funding of 5% or 10% of their home purchase price through Canada Mortgage and Housing Corporation (CMHC).
To be eligible:
Household income is less than $120,000.
There is a cap of no more than 4 times the applicant’s annual income where the mortgage value plus the CMHC loan doesn’t exceed $480,000.
The buyer must pay back CMHC when the property is sold, however details about the dollar amount payable is unclear. There will be further details released later this year.
Canada Training Benefit
A refundable training tax credit to provide up to half eligible tuition and fees associated with training. Eligible individuals will accumulate $250 per year in a notional account to a maximum of $5,000 over a lifetime.
Canadian Drug Agency
National Pharmacare program to help provinces and territories on bulk drug purchases and negotiate better prices for prescription medicine. According to the budget, the goal is to make “prescription drugs affordable for all Canadians.”
Registered Disability Savings Plan (RDSP)
The budget proposes to remove the limitation on the period that a RDSP may remain open after a beneficiary becomes ineligible for the disability tax credit. (DTC) and the requirement for medical certification for the DTC in the future in order for the plan to remain open.
This is a positive change for individuals in the disability community and the proposed measures will apply after 2020.
Intergenerational Business Transfer
The government will continue consultations with farmers, fishes and other business owners throughout 2019 to develop new proposals to facilitate the intergenerational transfers of businesses.
Employee Stock Options
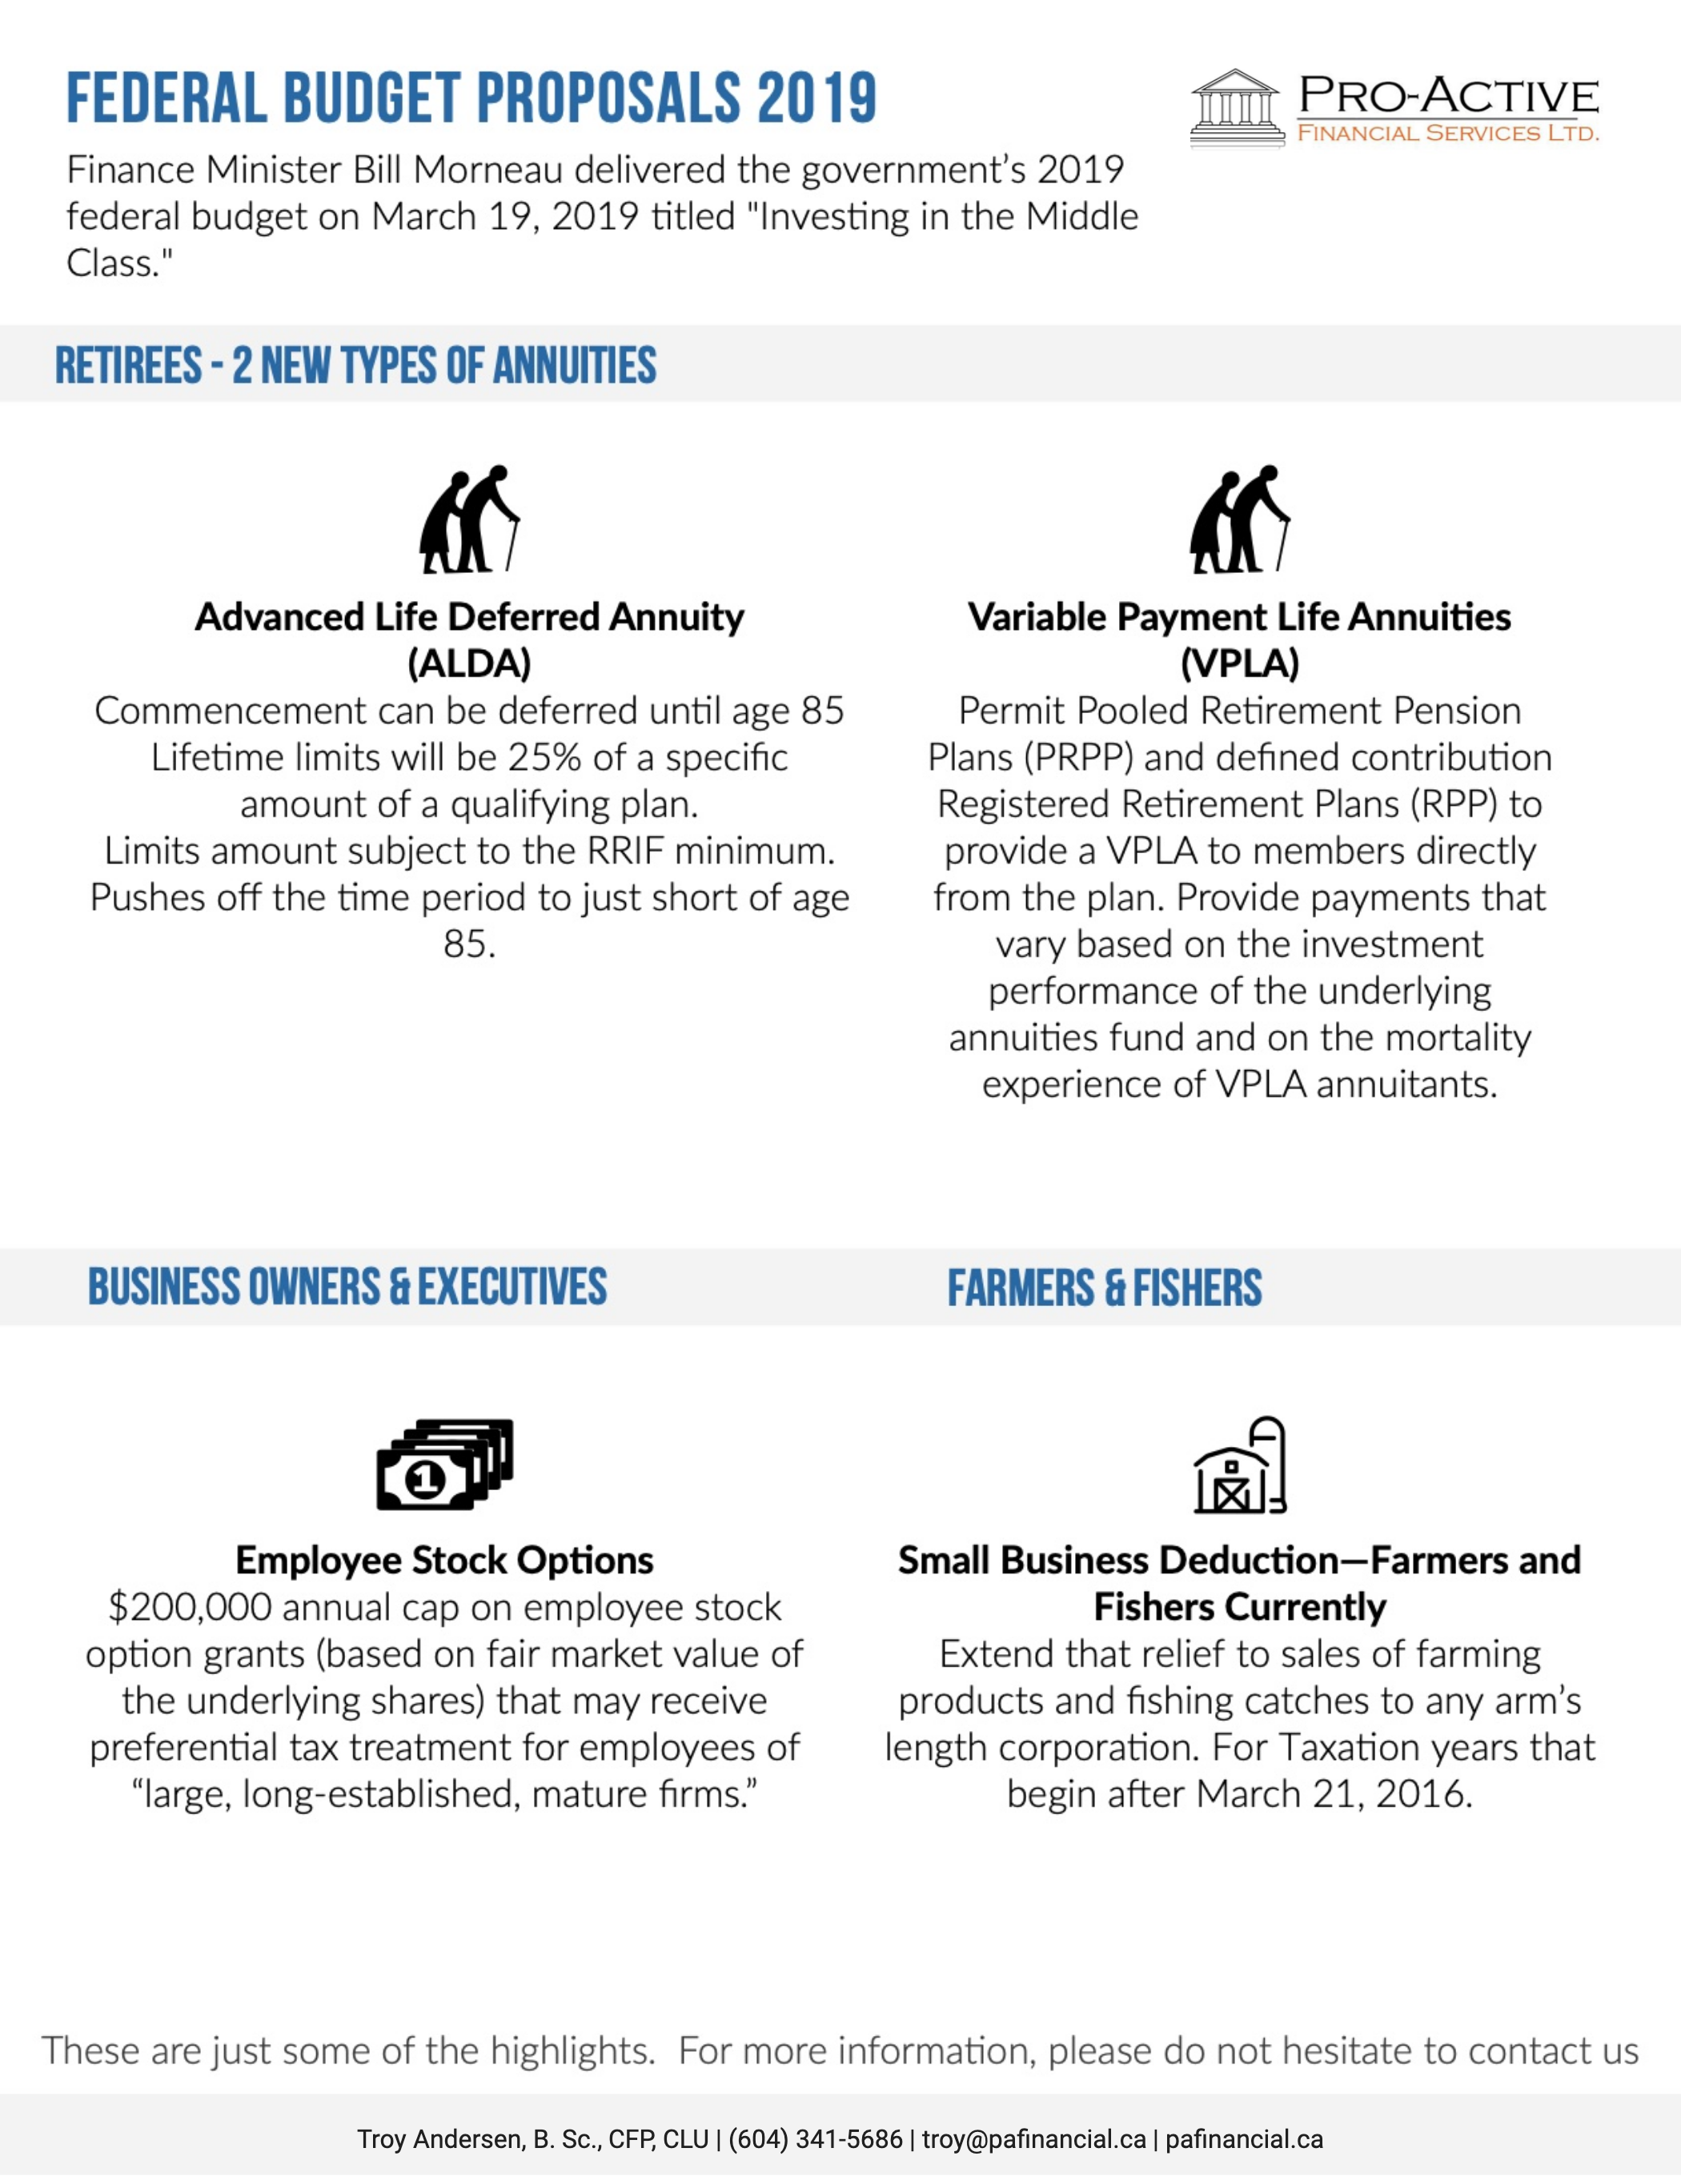
The introduction of a $200,000 annual cap on employee stock option grants (based on Fair market value) that may receive preferential tax treatment for employees of “large, long-established, mature firms.” More details will be released before this summer.
Additional types of Annuities under Registered Plans
For certain registered plans, two new types of annuities will be introduced to address longevity risk and providing flexibility: Advanced Life Deferred Annuity and Variable Payment Life Annuity.
This will allow retirees to keep more savings tax-free until later in retirement.
Advanced Life Deferred Annuity (ALDA): An annuity whose commencement can be deferred until age 85. It limits the amount that would be subject to the RRIF minimum, and it also pushes off the time period to just short of age 85.
Variable Payment Life Annuity (VPLA): Permit Pooled Retirement Pension Plans (PRPP) and defined contribution Registered Retirement Plans (RPP) to provide a VPLA to members directly from the plan. A VPLA will provide payments that vary based on the investment performance of the underlying annuities fund and on the mortality experience of VPLA annuitants.
Small Business Deduction
Farming/Fishing will be entitled to claim a small business deduction on income from sales to any arm’s length purchaser. Producers will be able to market their grain and livestock to the purchaser that makes the most business sense without worrying about potential income tax issues. This measure will apply retroactive to any taxation years that began after March 21, 2016.
To learn how the budget affects you, please don’t hesitate to contact us.
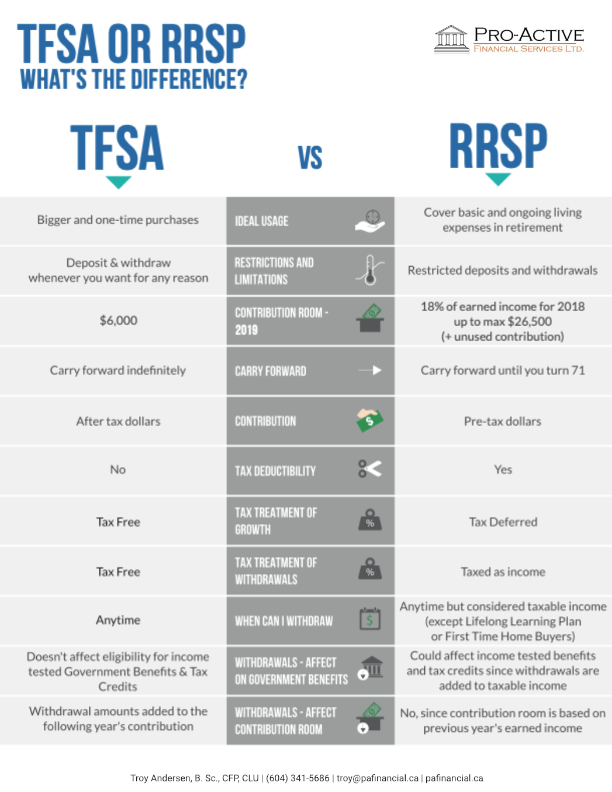
If you are seeking ways to save in the most tax-efficient manner available, TFSAs and RRSPs can both be effective options for you to achieve your savings goals more quickly. However, each plan does have distinct differences and advantages / disadvantages. Let’s take a look at their key features:
While a TFSA can be used for any type of savings, an RRSP is used exclusively for retirement savings.
You can enjoy tax free withdrawals from your TFSA due to the fact that you make your contributions after you have paid tax, whereas the opposite is true for withdrawals from your RRSP (except in the case of lifelong learning plan and home buyers’ plan)
TFSA contributions aren’t tax deductible whereas RRSP contributions are i.e. with an RRSP, you can deduct the contributions that you make from your income when you file your tax return.
It is required that you use earned income to contribute towards your RRSP but this is not the case for your TFSA.
You can continue to contribute towards your TFSA for as long as you like, whereas you must close your RRSP and stop contributing towards it when you turn 71 and purchase an annuity or convert it to a RRIF with the savings that you have made within the plan.
You are able to specify your spouse as your beneficiary with both your TFSA and your RRSP, however there is a key difference with how your savings are treated upon your spouse’s death. With an RRSP, there will be taxes payable upon the monies left in the plan by your children who inherit it, whereas with a TFSA, tax is only paid on the increase in the value of the plan since the date of death in the year that it is inherited by your children. What’s more, no tax is payable if the value that they receive is less than the value of the TFSA at the time of death.
In summary, your individual circumstances will dictate which plan is the most appropriate for you, depending on your tax position and withdrawal intentions. The primary difference between both plans is the timing of the taxes payable i.e. if you want to defer the payment of your taxes, particularly if your marginal tax rate will be lower in retirement, an RRSP may be more beneficial for you. Alternatively, if your marginal tax rate will be higher when you plan to make withdrawals, a TFSA may suit you better.
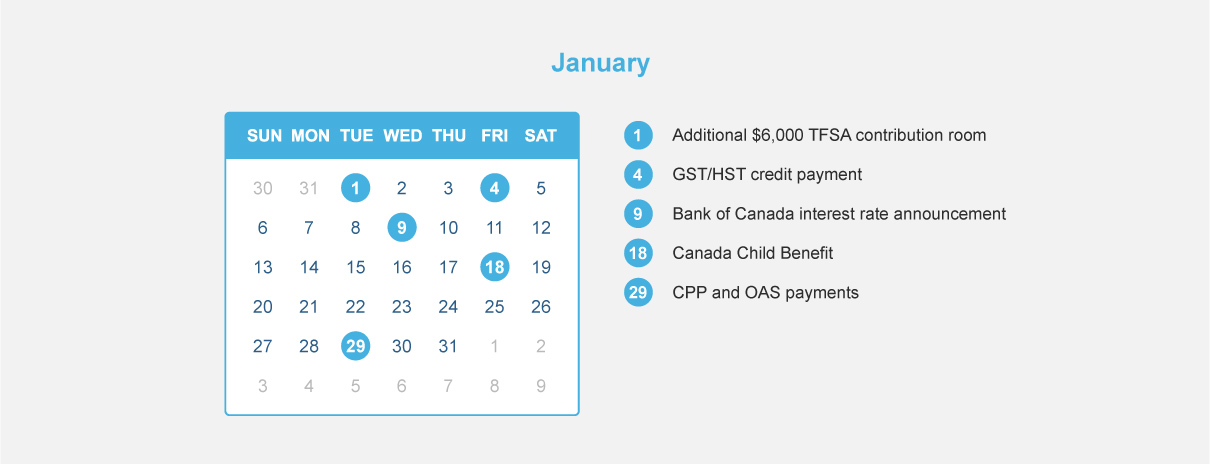
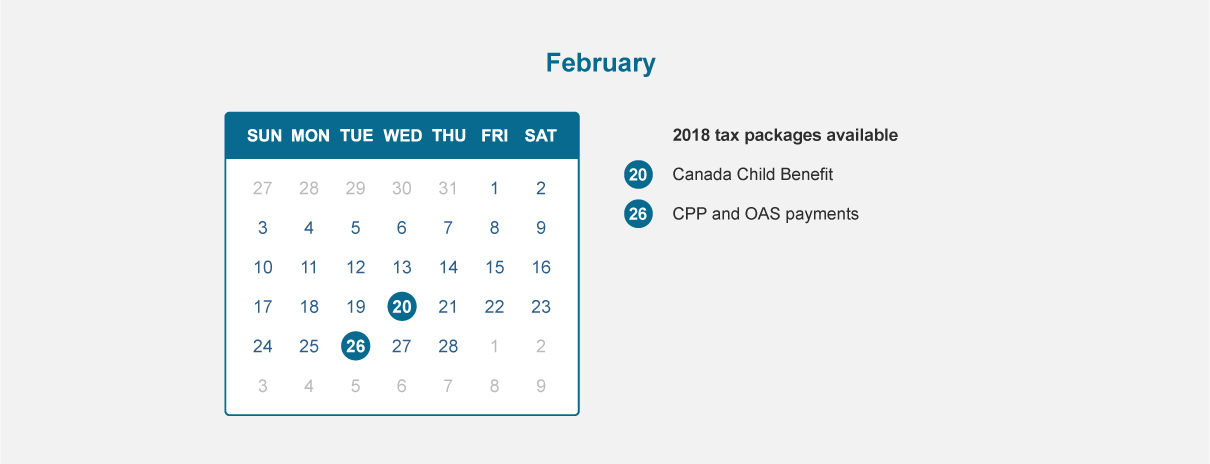
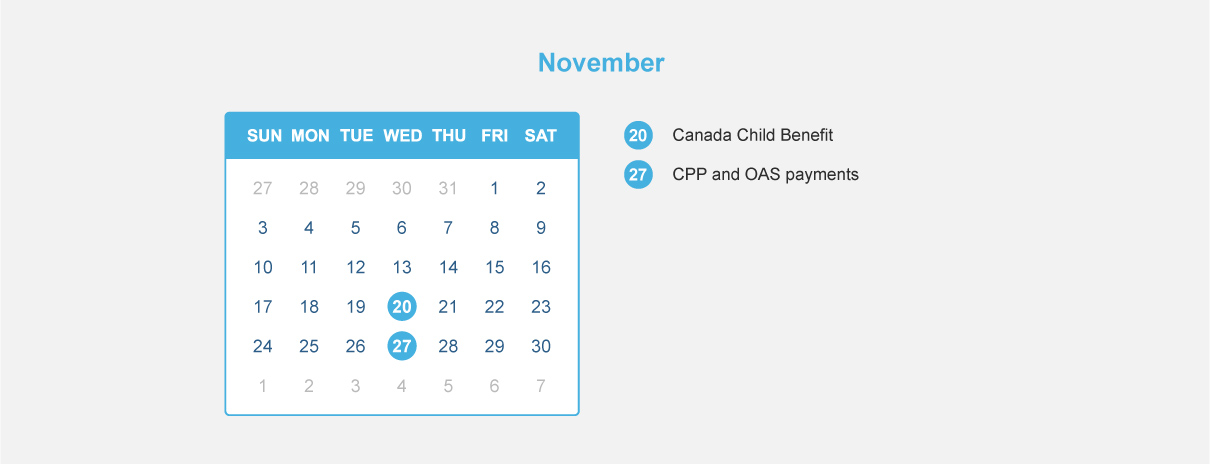
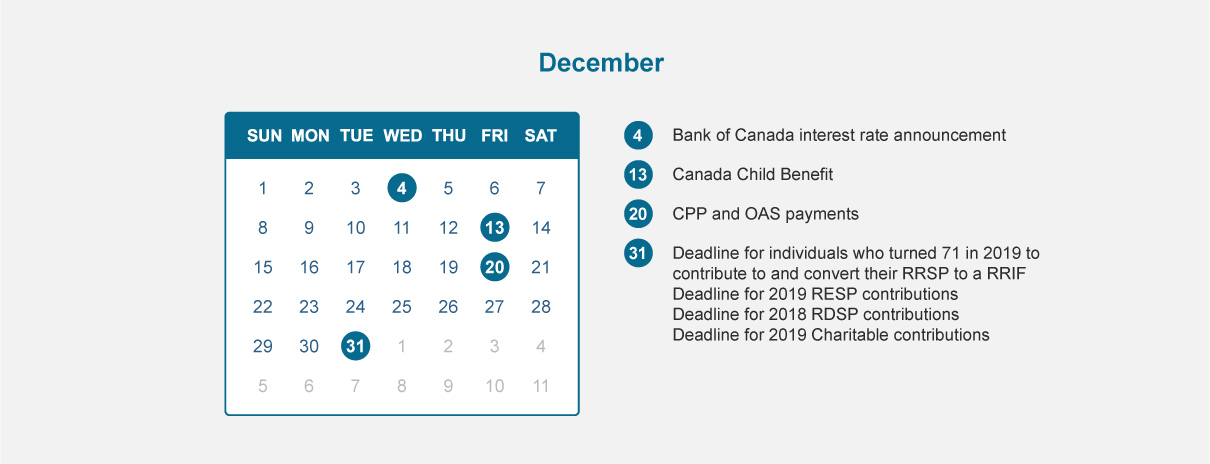
Financial Calendar for 2019 – All the deadlines you need to know to maximize your benefits!
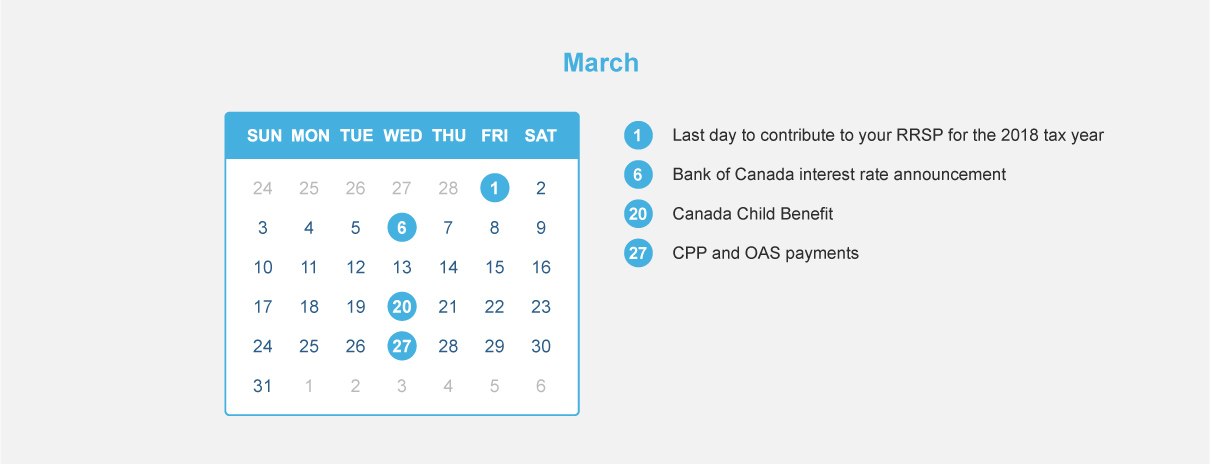
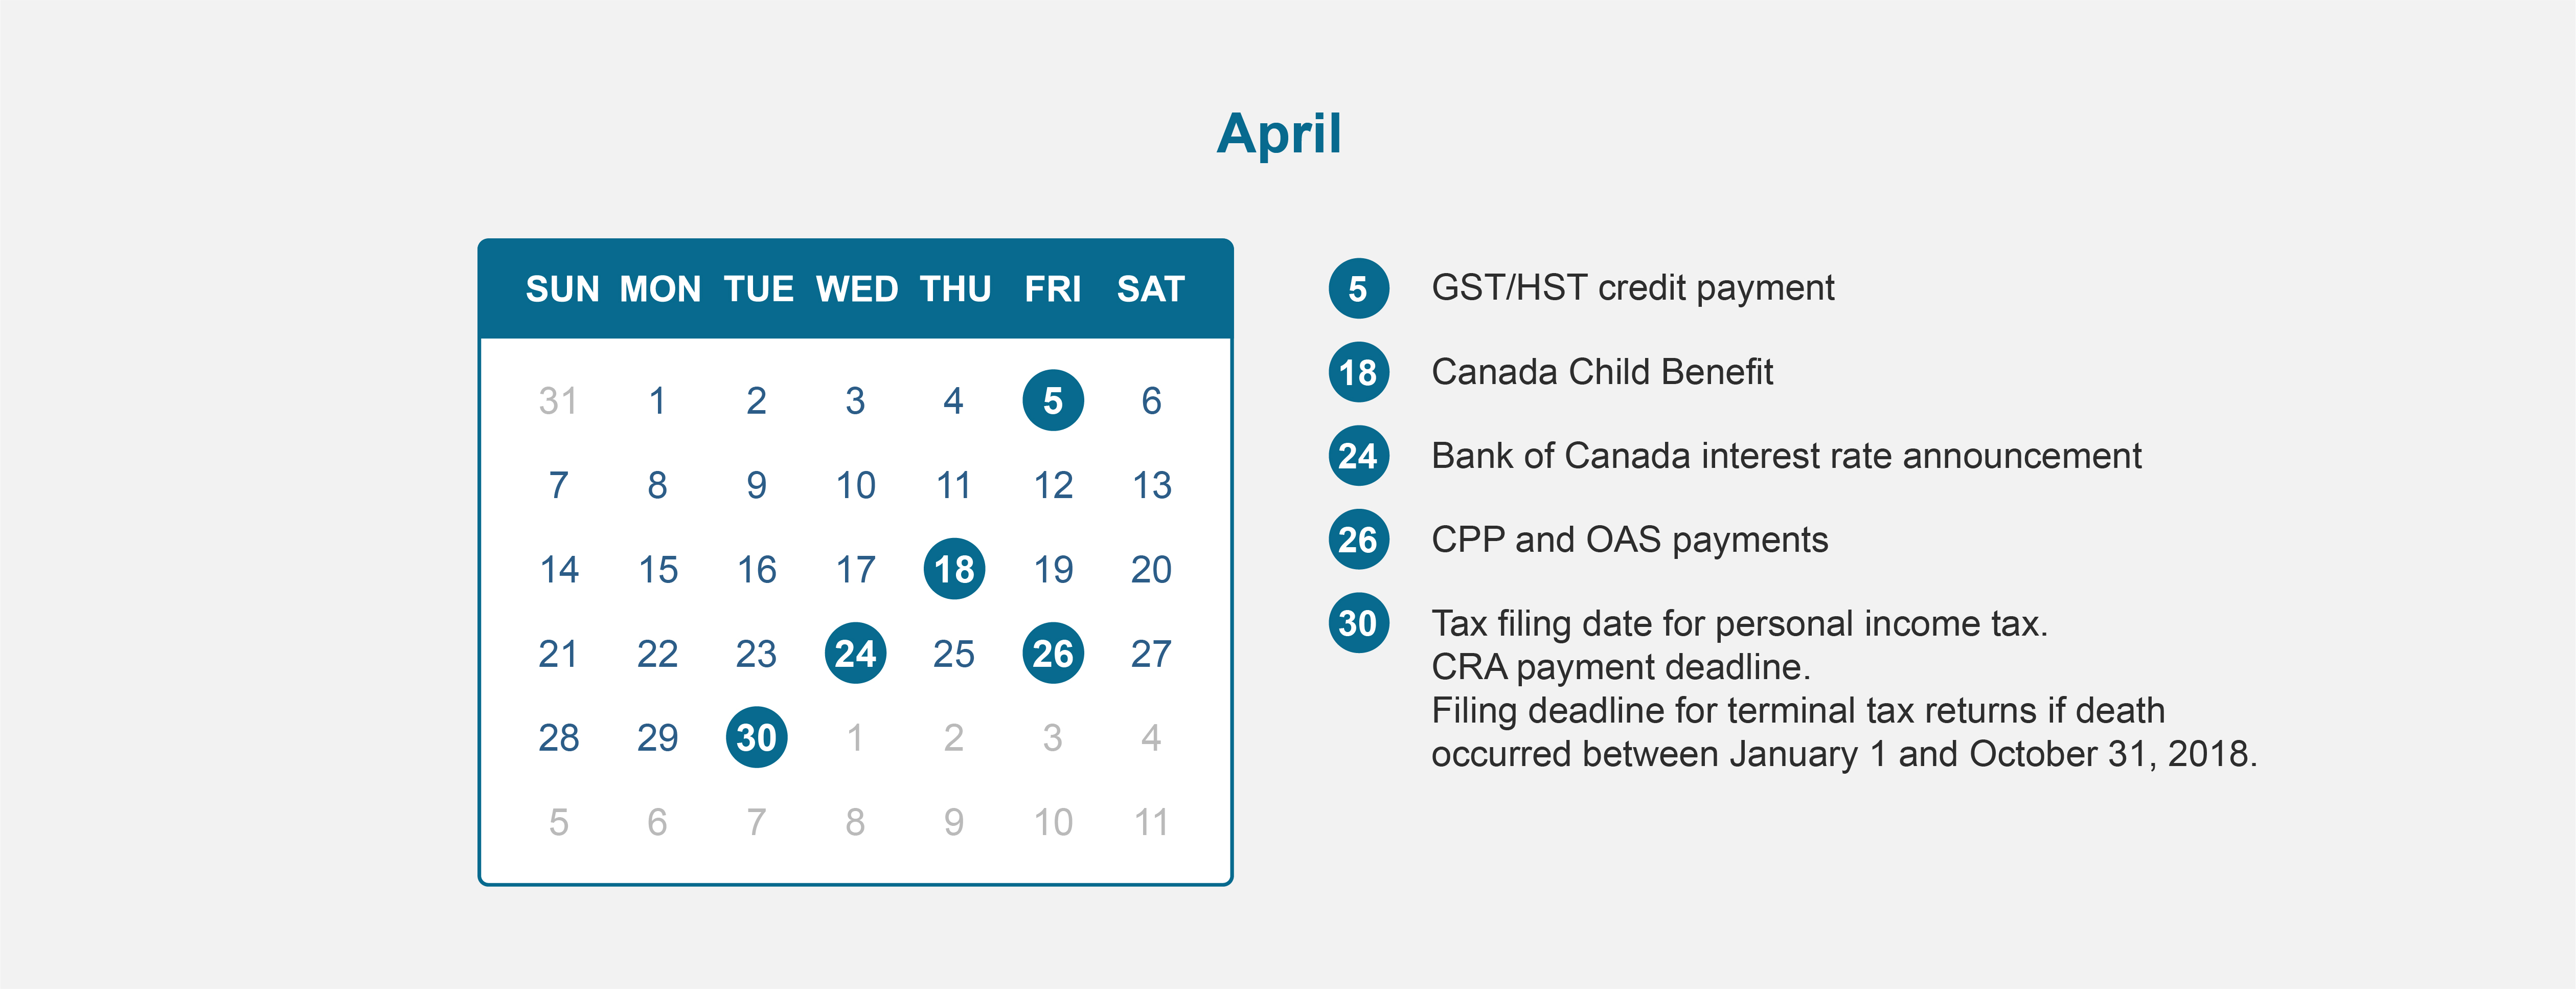
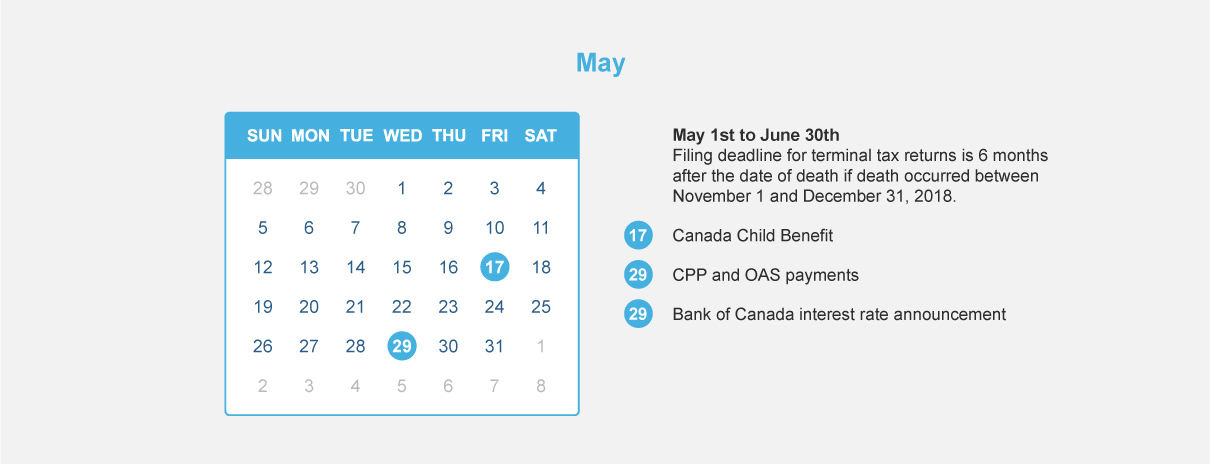
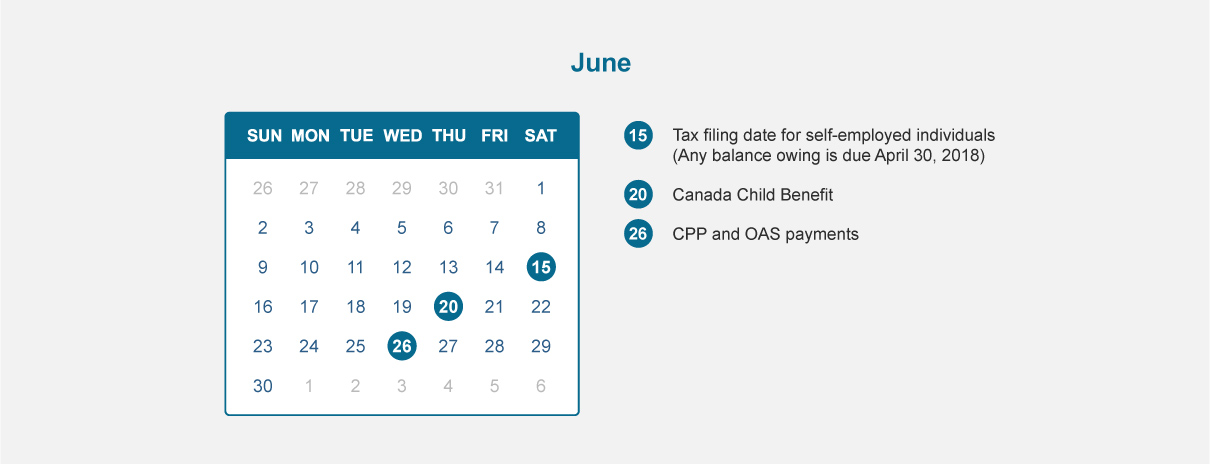
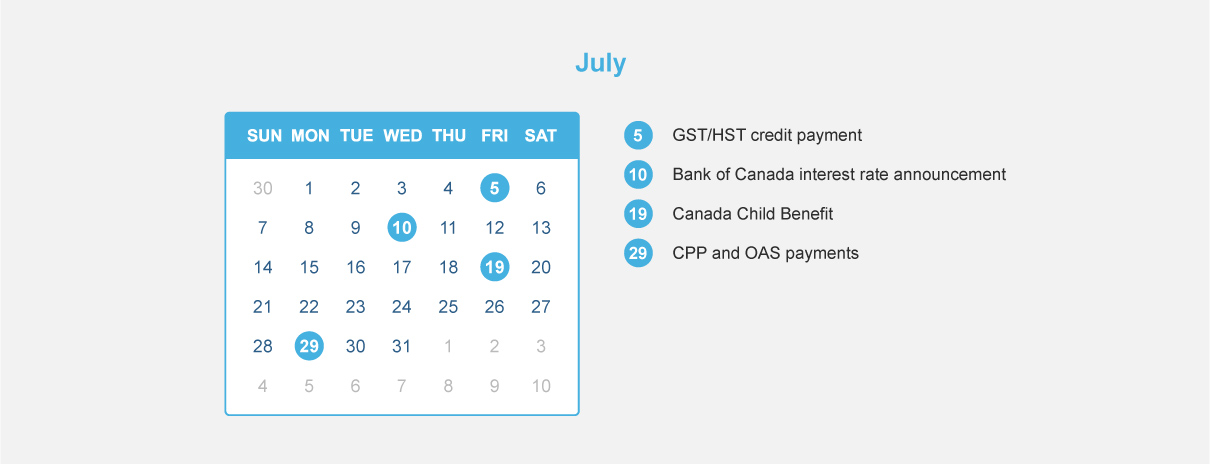
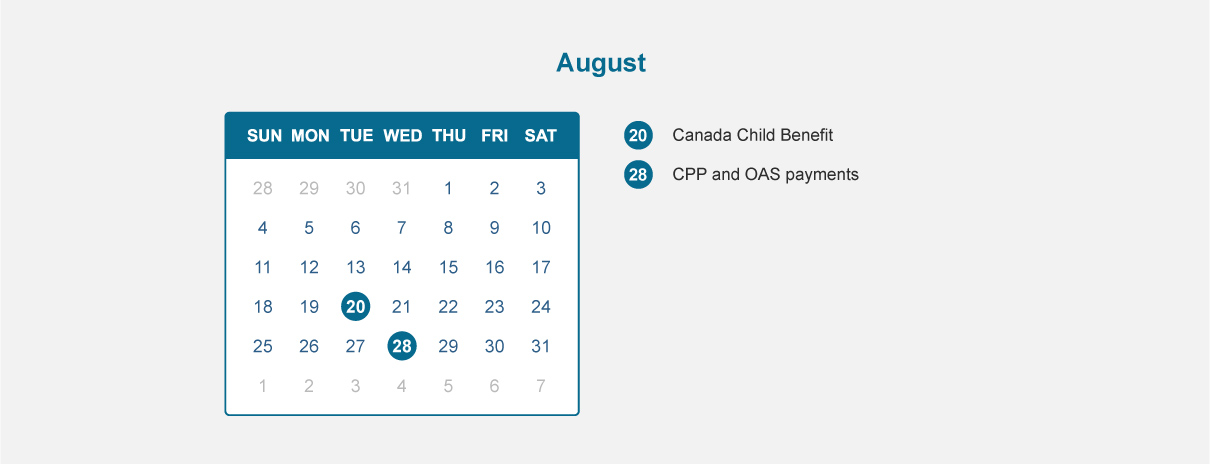
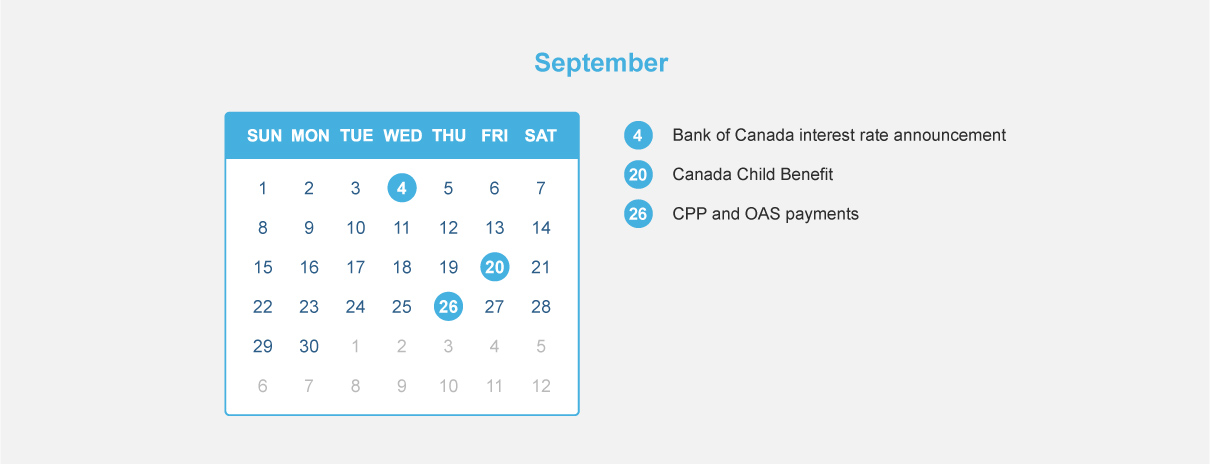
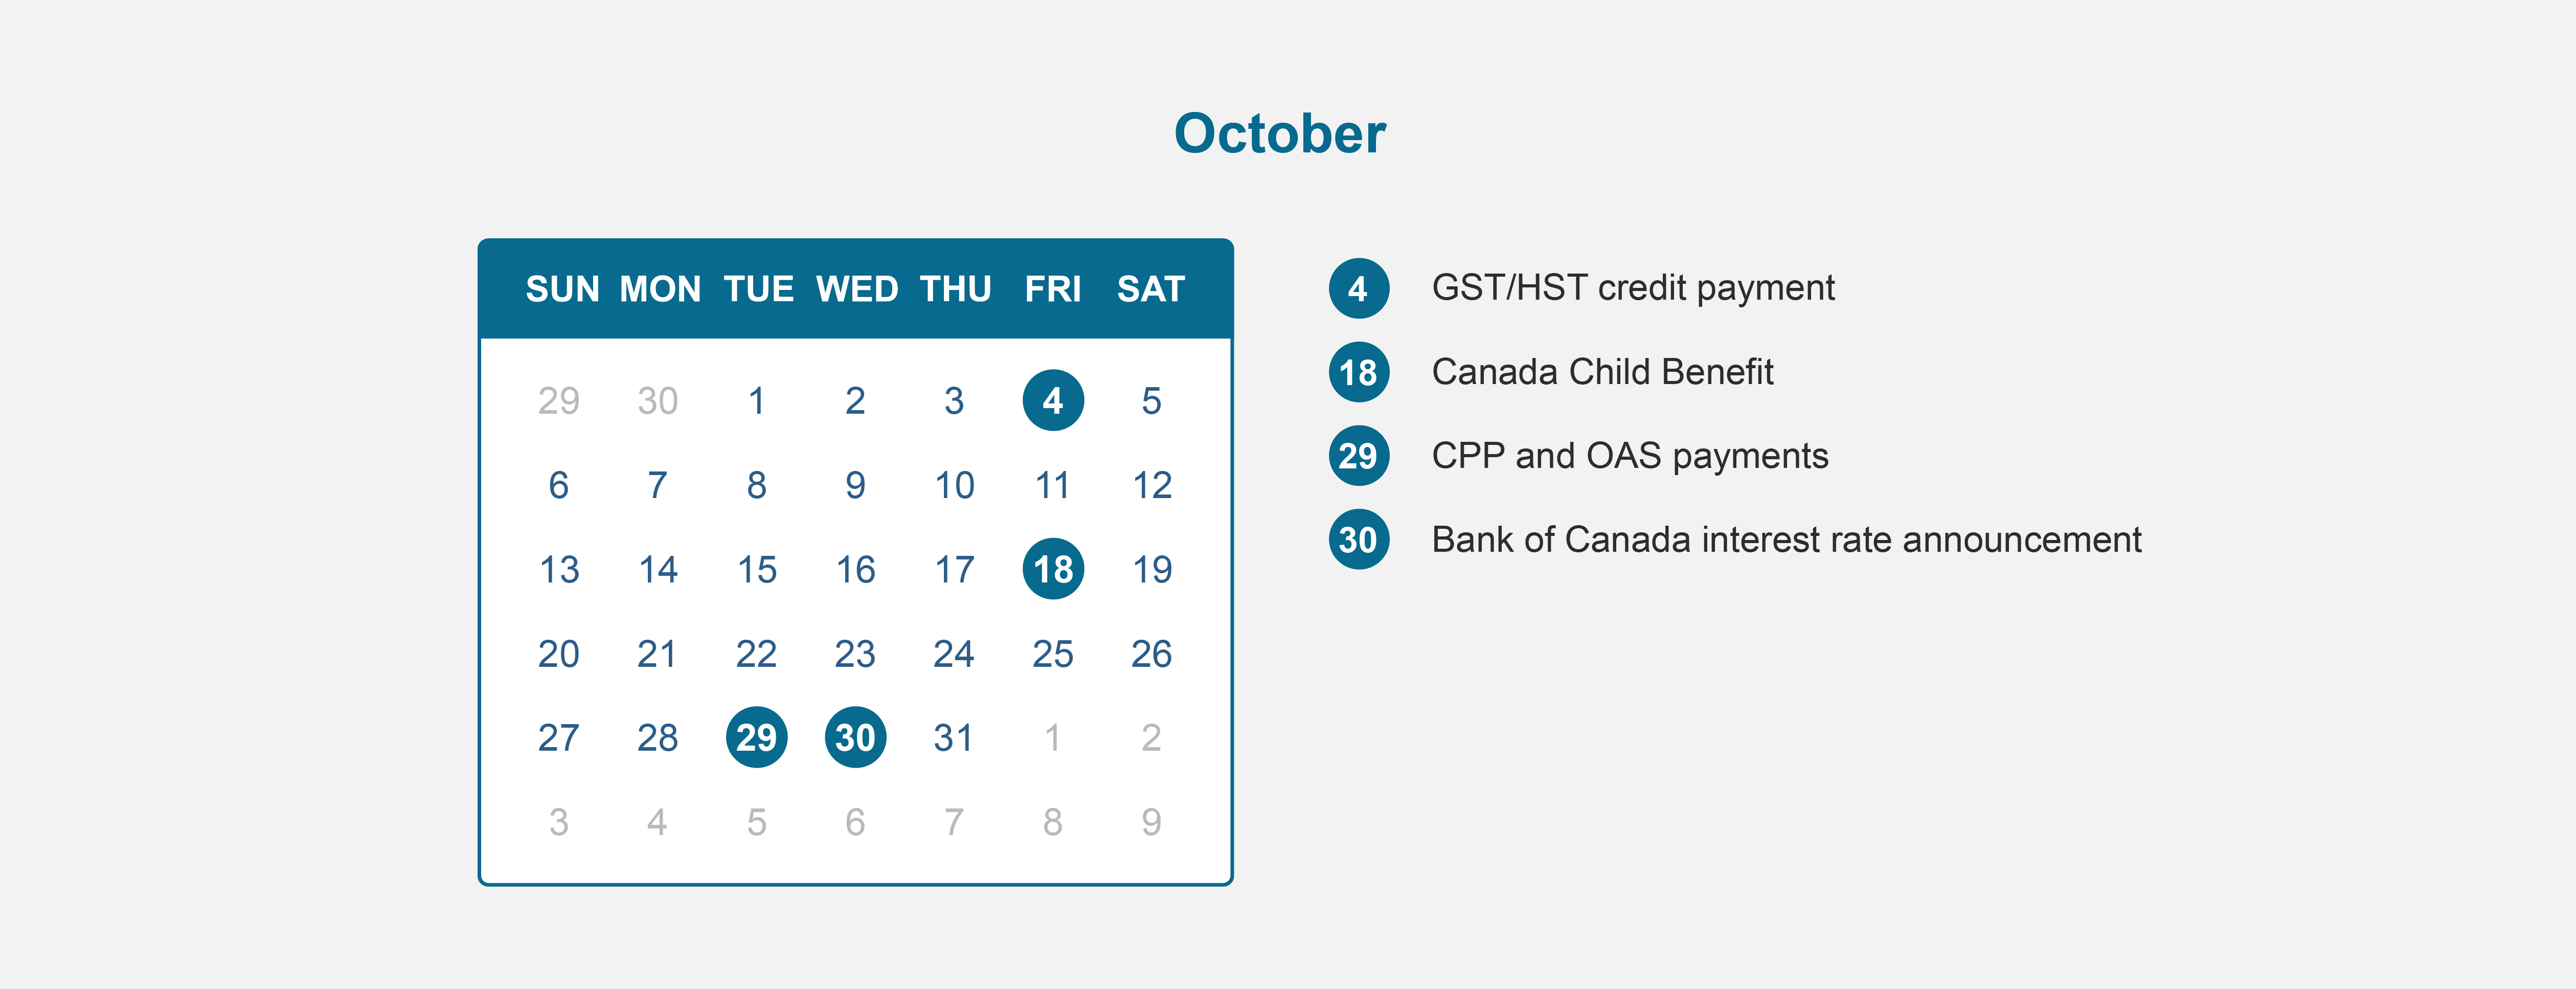
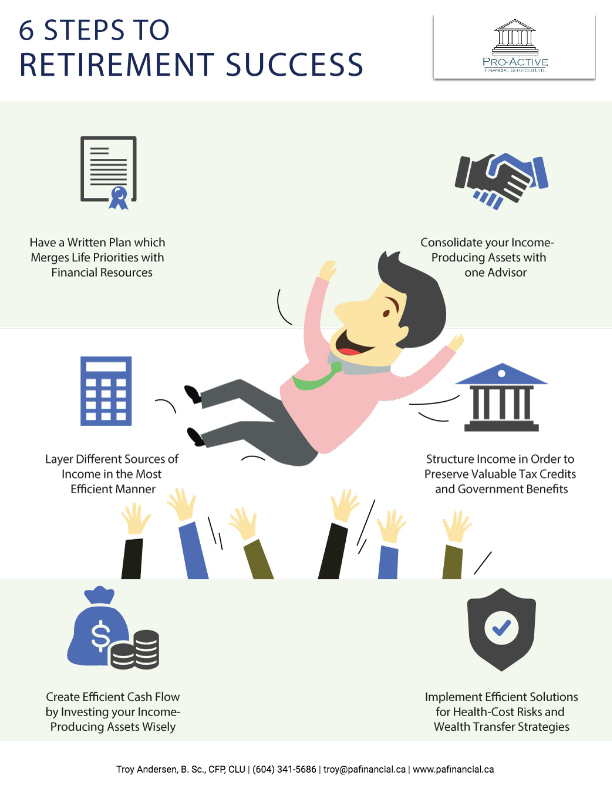
Retirement planning can be challenging, we’ve outlined what we feel are 6 steps to retirement success.
Talk to us about a complimentary comprehensive review of your retirement plan.

How to Make the Best of Inheritance Planning
Inheriting an unexpected, or even an anticipated, lump sum can fill you with mixed emotions – if your emotional attachment to the individual who has passed away was strong then you are likely to be grieving and the thought of how to handle your new-found wealth can be overwhelming and confusing but also exciting. One of the best pieces of advice in this situation is to give yourself some time before making any binding financial decisions. The temptation to quickly put the money to so-called ‘good use’ or to rush out and spend it can be strong but you must allow the news to sink in and also take some time to consider your options before you embark on the process of dealing with the inheritance. In the short term, put the money away in a high interest savings account and take time to research and think carefully about your financial goals and objectives and how this inheritance can help you to secure and maximise your financial future in the best way.
Although there is no one-size-fits-all approach to dealing with larger sums of money, here are some useful ideas of where to start.
Reduce your debt burden
If you have significant or high-interest debts, one of the safest options of all is paying this debt down. Not only will you achieve a guaranteed after-tax rate of return of your current interest rate, it can also add to your feeling of financial security and potentially offer you a more consistent financial picture. Debt often carries with it a significant interest rate – particularly on credit cards and overdrafts for example – so in many cases, eliminating this burden should be considered as one of your main priorities.
However, you may like to take careful note of the option below regarding investing the money instead as much depends on the prevailing interest rates and, of course, your appetite for risk, as you may well find an investment option with a potentially higher return more attractive.
Make investments
A particularly effective way of investing an inheritance is to add it to your retirement savings – especially if your nest egg is not looking quite as healthy as it should due to missed savings years for example. Those with lower or less reliable incomes should look upon this option as a great choice in particular.
Be charitable
After considering your own future financial needs, giving some of your wealth away to either charities or to family and friends is a good option to share out some of your inheritance to those who could benefit from it. What’s more, donating to charity can also offer you some tax breaks which may reduce your overall tax burden.
Many individuals see this philanthropic route as offering them the opportunity to do something meaningful and rewarding with their wealth and contributing towards their own sense of moral duty and emotional wellbeing.
Make a spending plan
Of course, you are likely to be keen to spend some of your wealth on yourself and your family, particularly if your financial situation means that you have previously had to be more careful and prudent with money than you would have liked. A great way to do this is to create a spending plan so that you can enjoy the benefits of spending, without it significantly eating into money set aside for your financial planning goals. You could, perhaps, aim to set aside 10% of the inheritance just for yourself and loved ones to enjoy. The proportion will naturally depend on your circumstances but, in principle, it’s a great idea as it allows you to balance sensible saving and investments with some short-term enjoyment of your wealth.
Talk to us, we can help.
 Budget 2026: What the New Federal Measures Could Mean for Your MoneyNovember 6, 2026 - 5:49 pm
 Health Spending Accounts and Wellness Spending AccountsNovember 4, 2026 - 12:50 am
 Critical Illness Insurance ExplainedOctober 6, 2026 - 6:25 pm
 RDSP Explained 2026September 2, 2026 - 11:00 pm
 Generic Ozempic Is Here. Will Your Drug Plan Actually Save Money?August 8, 2026 - 8:30 am